
Small business loan approval can feel slow when every day matters. A lender may need time to review credit, cash flow, tax returns, bank statements, debt, collateral, and the purpose of the loan. However, many delays happen before the lender ever makes a decision.
Missing documents, inconsistent numbers, unclear funding requests, and slow responses can all hold up an otherwise reasonable application. A prepared borrower gives the lender less to chase and fewer reasons to pause the file. That does not guarantee approval, but it can help reduce avoidable delays.
The goal is to make your application easier to review. When your request is clear, your records are organized, and your communication is prompt, the loan process usually has a better chance of moving smoothly.
Why Small Business Loan Approval Takes Time
Lenders do not approve business loans based only on a short application form. They need to understand whether the business can repay the loan, how the money will be used, and what risks may affect repayment. That review takes time, especially when the application is incomplete or the business situation is complex.
For SBA-backed loans, the process can also depend on the loan size, lender processing method, and borrower circumstances. SBA notes that application contents vary, and the lender helps determine which documents are needed. That is one reason two businesses may have very different timelines, even when they apply for similar loan amounts.
Speed also depends on the lender. Online lenders may move faster on some products, while traditional banks and SBA lenders may require more documentation. A faster lender is not always the better lender, so business owners should compare speed, cost, repayment terms, and reliability together.
Start With a Clear Funding Request
Before applying, know exactly how much money you need and why you need it. A request for “extra capital” is harder to review than a request for a specific amount tied to inventory, equipment, payroll timing, expansion, or working capital. Clear funding requests help lenders understand the purpose of the loan more quickly.
For example, asking for $75,000 to replace aging equipment and increase production capacity is stronger than asking for a general cushion. The lender can evaluate the amount, the use of funds, and the expected business benefit. That clarity also helps you avoid borrowing more than the business can comfortably repay.
Be ready to explain how the loan supports revenue, stability, or efficiency. If the money will solve a cash-flow timing problem, say so. If it will fund a purchase that improves operations, explain how the investment should help the business repay the loan.
Review Credit and Financial Health Before Applying
Credit problems can slow down small business loan approval, especially when the borrower discovers them after applying. Review both personal and business credit reports before you submit an application. If there are errors, outdated accounts, or unresolved issues, address them as early as possible.
Lenders may also review business revenue, debt payments, cash flow, profitability, bank activity, and owner contributions. Strong records make that review easier. If your numbers are disorganized, the lender may need more follow-up, which can add days or weeks to the process.
If your business is not quite ready, it may be worth strengthening your application before applying. Our guide on how to qualify for a small business loan explains steps that may help borrowers prepare before approaching a lender.
Organize Documents Before the Lender Asks
Missing paperwork is one of the most common reasons a loan file slows down. Before applying, ask the lender what documents are required for your loan type and business situation. Do not rely on a generic checklist if the lender has specific instructions.
Common documents may include business and personal tax returns, bank statements, profit-and-loss statements, balance sheets, formation documents, business licenses, owner identification, debt schedules, and information about collateral. SBA regulations also describe common application contents such as loan amount and purpose, business history, financial statements, tax information, collateral, and a business plan when applicable.
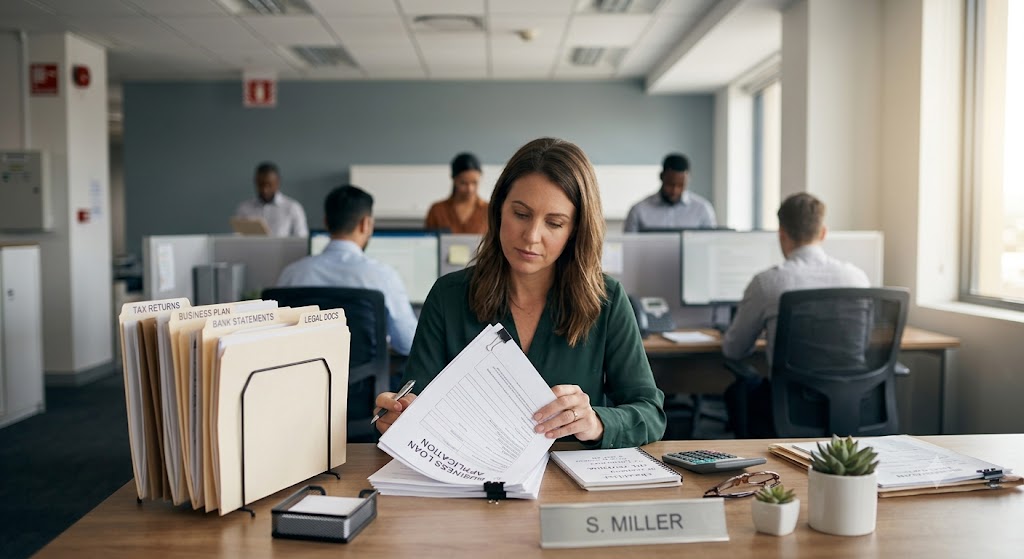
Create a digital folder for the application and label documents clearly. A small business document organizer can also help keep paper copies together if you still maintain physical records. The goal is simple: when the lender asks for something, you should know exactly where it is.
Make Your Financial Statements Easy to Understand
Financial statements should be current, consistent, and easy to read. If your profit-and-loss statement says one thing and your tax return suggests something very different, the lender may need clarification. That does not always mean there is a problem, but unexplained differences can slow the review.
Check your revenue figures, expense categories, debt payments, and owner draws before submitting. Make sure the time periods match what the lender requested. If you use bookkeeping software, review reports for obvious errors before exporting them.
It may also help to include a brief explanation of unusual changes. A one-time equipment purchase, temporary shutdown, large customer payment, or seasonal dip can make the numbers look confusing without context. A clear explanation can help the lender understand the story behind the financials.
Choose a Lender That Fits Your Timeline
Different lenders move at different speeds. A bank that knows your business may review your file more efficiently than a lender seeing your records for the first time. Online lenders may offer faster decisions on some products, but speed can come with higher costs or shorter repayment terms.
SBA loans may be a good fit for many qualified small businesses, but they often involve more documentation than some conventional or short-term options. SBA Lender Match can help connect businesses with lenders, but SBA describes it as a matching tool rather than a loan application. After you submit a Lender Match request, SBA says it prepares a summary of interested lenders two business days later.
Compare the full offer, not just the speed of response. Review the interest rate, APR, fees, repayment schedule, collateral requirements, and personal guarantee language. If you need help comparing rate language, our guide on APR vs interest rate can help you understand why the advertised rate does not always show the full cost.
Make Your Business Plan Easy to Review
Not every loan requires a long business plan, but many lenders want to understand how the business operates and how the loan will be repaid. A useful plan does not need to be filled with jargon. It should explain what the business does, who it serves, how it earns money, and how the requested funds will support repayment.
Keep the plan organized and direct. Include revenue history, reasonable projections, customer base, market position, owner experience, and repayment strategy. If the lender asks for a shorter summary, provide that instead of sending a large document the reviewer must sort through.
For SBA loans, a business plan may be required depending on the situation. That is another reason to ask the lender what it needs before applying. A plan that matches the lender’s expectations can prevent unnecessary back-and-forth.
Communicate Clearly With the Lender
Good communication can help keep the process moving. Introduce yourself, confirm the best contact person, and ask how the lender prefers to receive documents. Some lenders want everything uploaded through a portal, while others may request secure email or a specific file format.
Ask what the next steps are before the file goes into review. It is reasonable to ask what documents are still missing, who will contact you with questions, and how often you should check for updates. Clear expectations can reduce confusion later.
If you have already worked with the lender, mention that history. Returning borrowers may still need to provide updated documents, but an existing relationship can sometimes reduce friction. Lender trust often grows when business owners communicate clearly and respond professionally.
Respond Quickly During Underwriting
Once the loan file is under review, watch your email, phone, and lender portal closely. A lender may ask for a missing statement, clarification about a deposit, updated financials, proof of insurance, or a signed form. Slow responses can push the file behind other applications.
Send documents in the exact format requested. If the lender asks for a PDF, do not send screenshots unless the lender says they are acceptable. If the lender asks for all pages of a bank statement, include every page, even blank ones.
When you do not understand a request, ask for clarification quickly instead of guessing. Sending the wrong document can create more delay than asking one clear question. Professional follow-through helps the lender keep the application moving.
Avoid Mistakes That Slow Loan Approval
Even strong applications can be delayed by small errors. Inconsistent revenue figures, missing signatures, outdated tax returns, blank fields, incorrect EIN information, and incomplete ownership details can all cause problems. These issues may seem minor, but they force the lender to stop and request corrections.
Review your application line by line before submitting. Make sure names, addresses, ownership percentages, loan amount, business structure, and tax information match your supporting documents. If more than one owner must sign, confirm that each required signature is included.
It is also wise to avoid applying to many lenders at once without a plan. Multiple incomplete applications can create confusion and make it harder to track what each lender needs. Choose lenders carefully and keep a simple record of where each application stands.
Prepare for Closing and Funding
Approval is not always the final step before money reaches your account. The lender may still need signed loan documents, proof of insurance, bank account verification, collateral paperwork, automatic payment authorization, or final closing conditions. Delays at this stage can hold up funding even after approval.
Ask the lender what will happen after approval so you are not surprised. If insurance, lien documents, lease information, or updated financials may be needed, start gathering them early. Preparing for closing helps prevent the process from stalling near the finish line.
Read the final documents before signing. Confirm the loan amount, repayment schedule, interest rate, fees, collateral, guarantees, and prepayment terms. Fast funding is helpful, but it should not come at the cost of misunderstanding the agreement.
Build a Faster Path for Future Applications
The easiest time to prepare for the next loan is before you need it. Keep tax returns, financial statements, bank records, licenses, insurance documents, formation papers, and debt schedules up to date. Strong organization can make future applications less stressful.
It also helps to maintain lender relationships between funding needs. Pay on time, communicate early if problems arise, and keep reliable financial records. Over time, lenders may view your business as easier to review because your information is complete and your history is consistent.
Future approval is never automatic, but preparation gives your business a better foundation. The more organized your records are, the easier it becomes to respond when an opportunity or cash-flow need appears.
Helpful Resources
- U.S. Small Business Administration: 7(a) Loans
- U.S. Small Business Administration: Lender Match
- 13 CFR § 120.191: Contents of a Business Loan Application
- SCORE: Business Plan Template
Final Thoughts
Small business loan approval usually moves faster when the borrower is prepared before the application begins. A clear funding request, organized records, current financial statements, and prompt communication can reduce avoidable delays. They also show the lender that the business owner understands the loan request and takes repayment seriously.
No article can promise fast approval, and no checklist can replace lender underwriting. Still, preparation matters. When your documents are ready and your numbers are clear, the lender can spend less time chasing details and more time reviewing the actual request.
If you are preparing for an SBA-backed loan, our related guide on applying for an SBA loan explains what lenders often review before making a decision.
Editor’s Note: This article was updated in August 2026 to improve readability, update source guidance, strengthen practical examples, and align the article with current Business Loan Press publishing standards.
This article is for general educational purposes only and should not be taken as legal, tax, accounting, financial, or lending advice. Business owners should review loan terms carefully and consult a qualified professional before making major borrowing decisions.
Amazon Affiliate Disclosure: As an Amazon Associate, Business Loan Press may earn from qualifying purchases. This does not change the price you pay.
Photo Credit: All images © Sloan Digital Publishing and licensed stock sources. Used with permission.