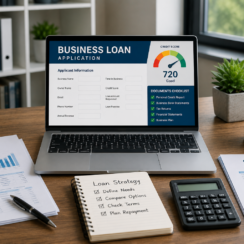
Qualifying for your first small business loan can feel intimidating, especially when you are growing from a side hustle. The good news is that lenders use a predictable checklist when they evaluate your application. You can prepare in advance and fix weak spots before you ever …
SBA loan rules changed in 2026, and small-business owners need to understand how the current requirements may affect eligibility, loan size, fees, and preparation.
A business line of credit may show one limit while allowing a much smaller draw. Learn how borrowing bases, eligible collateral, advance rates, reserves, and existing balances determine what is actually available.
Interest-only business loan payments can improve cash flow now, but principal remains. Learn what happens to later payments, total cost, and repayment risk.
Business loan denied? Learn how to identify the reason, fix the underlying problem, and decide when to reapply or consider another option.
One large customer can strengthen sales while weakening a loan application. Learn how lenders may calculate customer dependence, examine contracts and receivables, stress-test cash flow, and judge a borrower’s plan for reducing the risk.
Buying an existing company can shorten the path to revenue, but the loan must fit the business. Learn how SBA financing, valuation, buyer equity, seller notes, due diligence, and transition planning work together.
Fixed vs variable interest rates can affect how predictable your business loan payments are and how much the loan may cost over time. This article explains how fixed and variable rates work, why the lowest starting rate is not always the safest choice, and what small …
Business loans for women entrepreneurs can help fund startup costs, equipment, inventory, hiring, marketing, and growth. This guide explains SBA loans, microloans, grants, alternative financing, lender challenges, credit preparation, discrimination concerns, and practical steps women business owners can take before applying.
A business may qualify for financing without pledging a specific asset, but no collateral does not mean no risk. Learn what lenders review, what guarantees and liens may still apply, and how to compare offers safely.