Accounts receivable mistakes often begin as minor process flaws. They can later become cash flow problems that disrupt decisions, timing, and stability. Many owners notice the pressure only after collections slow and reserves begin to shrink.
That delayed recognition makes receivables risk especially costly. The damage usually builds quietly, long before a formal crisis appears. A business can look profitable on paper while its available cash weakens month after month.
Receivables should not be treated as a back-office detail. They support payroll, inventory, vendor timing, and growth. When that system slips, the business loses flexibility even if sales remain strong.
Why Delayed Collections Hurt More Than Many Owners Expect
Slow collections do more than postpone incoming cash. They reduce management’s confidence about when money will actually be available. That uncertainty affects staffing, purchasing, vendor relations, and planning.
It also changes the quality of decision-making. When cash timing becomes unreliable, managers often start reacting instead of directing. Useful investments may be postponed while urgent financing becomes more tempting.
Revenue can remain strong while cash availability deteriorates. Receivables may rise at the same time bank balances fall. That disconnect can remain hidden until payroll, taxes, or a major payable comes due.
Weak Credit Screening Before the Sale
One of the most expensive accounts receivable mistakes can happen before an invoice exists. Companies sometimes extend terms too easily because they want to close the sale. In that moment, optimism can replace financial discipline.
Not every customer deserves the same terms. Payment history, industry risk, order size, and customer concentration can all matter. A business that ignores those factors may create avoidable collection pressure from the start.
Good receivables management begins with customer qualification. That does not require hostility or excessive paperwork. It requires clear standards for who receives terms, how much credit is appropriate, and when exceptions need approval.
Inconsistent Invoicing Practices
Delayed billing remains one of the simplest operational mistakes. A company cannot collect quickly if it invoices slowly. Yet many businesses still treat invoicing as something that happens when time allows.
Waiting several days after shipment or project completion lengthens the cash cycle immediately. The effect becomes more serious when that delay repeats across many accounts. Small billing lags can add up quickly.
Accuracy matters just as much as speed. Incomplete invoices invite disputes, routing delays, and excuses for nonpayment. Missing purchase order numbers or billing details can add unnecessary days to the cycle.
Standardization helps prevent these problems. Billing should follow a defined schedule with clear documentation requirements. Once invoicing becomes routine and prompt, collections can improve without aggressive chasing.
Unclear Payment Terms and Weak Documentation
Payment terms should be specific, visible, and easy to understand. Too many businesses rely on assumptions that customers may not share. When terms are unclear, collection conversations become harder.
Customers should know the due date, discount terms, late-fee policy, and dispute process when those provisions apply. Clear expectations reduce confusion and leave less room for delay. They also make internal follow-up more consistent.
This is especially important for service businesses and custom project work. Scope changes, milestone billing, and approval triggers should be documented carefully. Otherwise, payment delays may reflect preventable ambiguity rather than inability to pay.
Failing to Use Aging Reports as an Early Warning System
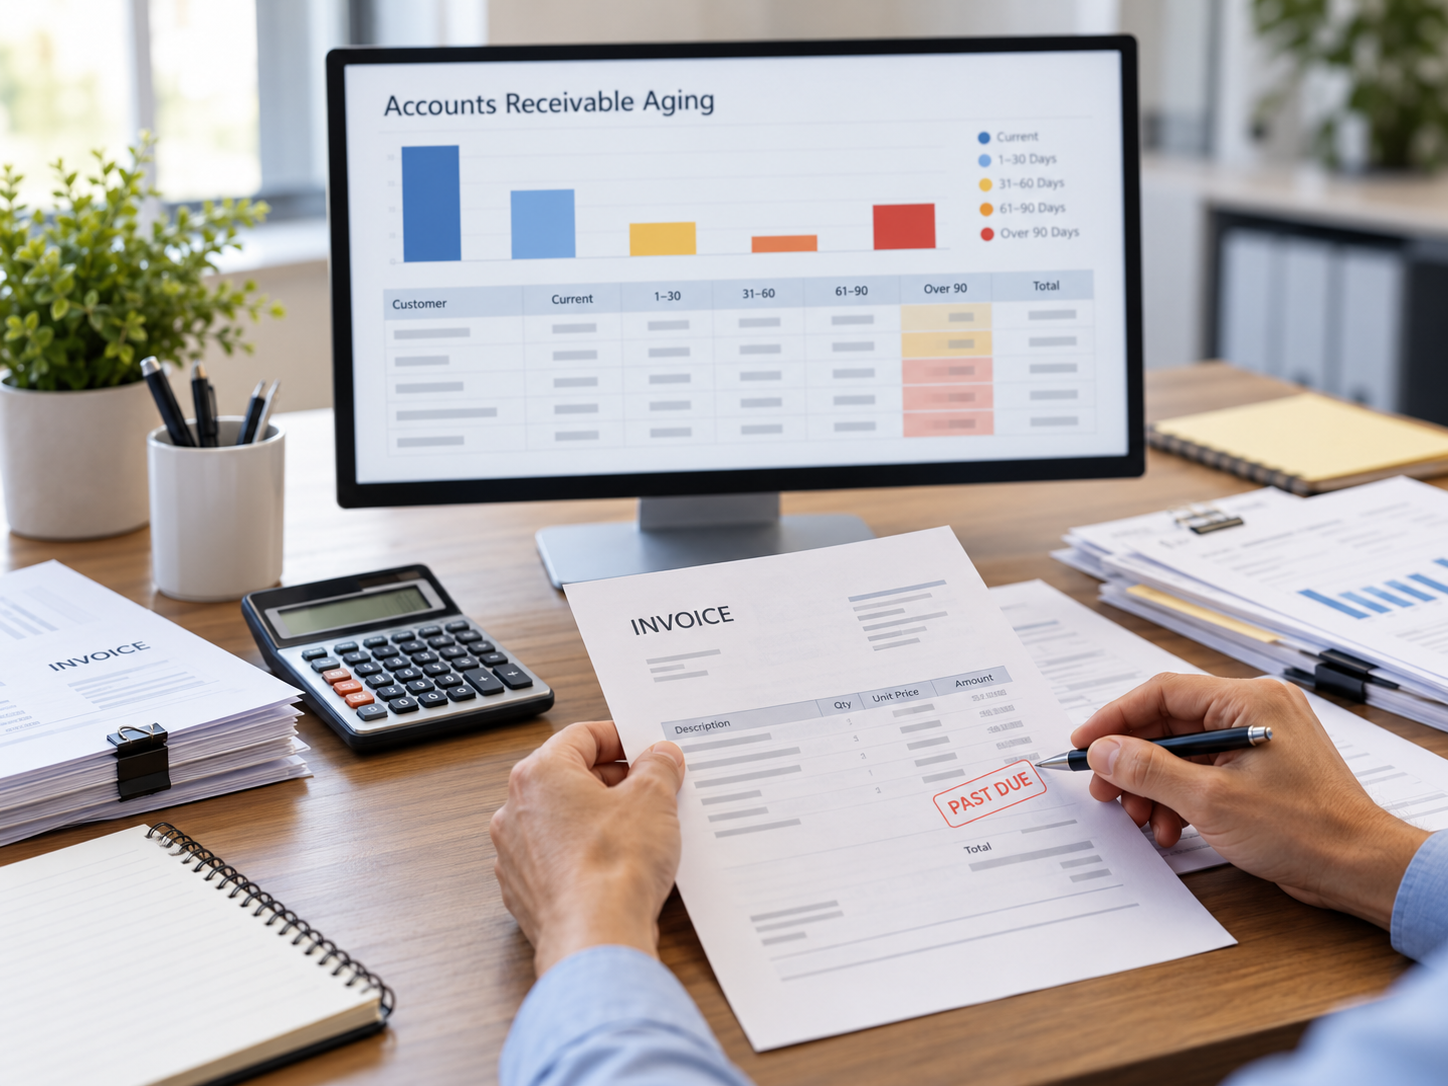
An aging report should function as an early warning system. Too often, it becomes a passive record reviewed only after problems deepen. That approach weakens collections and can hide concentration risk.
Owners need more than a total receivables number. They need to know who owes money, how long balances have been open, and whether delays are spreading. Aging categories help show whether the issue is isolated or systemic.
A reliable customer that begins drifting from current to overdue deserves attention quickly. Early intervention is usually easier than late-stage recovery. Routine review also prevents teams from normalizing balances that should have triggered action.
For a broader view of receivables timing, see our guide to the cash conversion cycle. It explains how receivables, inventory, and payables interact.
Avoiding Difficult Collection Conversations
Many collection failures stem from hesitation rather than strategy. Staff members may delay contact because they do not want to appear aggressive. Owners sometimes do the same when an important customer is involved.
That hesitation can become expensive. Silence may communicate flexibility that was never intended. Once late payment becomes comfortable for the customer, recovery often becomes slower and more awkward.
Professional collection practices do not require hostility. They require consistency, clarity, and timely escalation. A courteous reminder sent early is usually easier than a tense conversation months later.
Businesses should define when contact begins, who makes it, and how escalation works. Without those standards, follow-up depends too heavily on personality. Process discipline should carry the work.
Overreliance on a Few Large Customers
Receivables risk becomes more dangerous when it is concentrated. A company may believe its customer list is healthy because sales are strong. Yet one or two accounts may control too much incoming cash.
That concentration can distort collection decisions. Management may avoid firm follow-up because it fears damaging an important relationship. The result can be a quiet shift of bargaining power toward the customer.
When a large payer slows down, the effects spread quickly. Payroll timing, vendor payments, and inventory purchases can all come under pressure. Borrowing needs may rise even though the original problem was delayed receipts.
Separating Receivables From Cash Flow Strategy
Some companies still manage receivables as an administrative function rather than a financial one. That separation weakens visibility. Collection decisions shape liquidity just as clearly as borrowing decisions do.
Receivables affect how much working capital remains trapped in the business. They can influence reliance on credit lines and short-term borrowing. They also affect confidence when management plans expansion or prepares for unexpected costs.
Owners should view receivables alongside payables, inventory, and financing structure. Our guide to accounts receivable management explains how stronger collection systems support broader cash flow control.
Slow collections can also push companies toward repeated short-term borrowing. Our article on fast financing dependence explains how temporary funding can become part of the operating cycle.
What Stronger Receivables Control Looks Like
Improvement usually begins with a few disciplined changes rather than a dramatic overhaul. Credit standards should be documented and applied consistently. Invoices should go out quickly, accurately, and according to a defined schedule.
Payment terms should be clear before work begins. Aging reports should be reviewed on a regular calendar. Collection follow-up should start early and escalate through a professional process.
Management should also track useful indicators over time. Days sales outstanding, aging distribution, dispute rates, and customer concentration can reveal whether conditions are improving. Trends often matter more than a single month’s result.
Technology can help, but software is not the cure by itself. Strong results usually come from standards, accountability, and management attention. Tools work best when they support an already disciplined process.
The U.S. Small Business Administration’s financial management guidance identifies several core responsibilities. These include accounts receivable, accounts payable, available cash, bank reconciliation, and payroll.
The FDIC Money Smart for Small Business program also includes a dedicated cash flow management module. The program was developed jointly with the U.S. Small Business Administration.
Receivables Discipline Supports Better Business Decisions
Good receivables management does more than speed up collections. It improves visibility, reduces unnecessary borrowing pressure, and gives management more room to make deliberate decisions. Those benefits extend well beyond the accounting department.
Financial stress often develops through a series of tolerated inefficiencies. Accounts receivable mistakes belong high on that list because they can weaken liquidity without immediately damaging reported revenue.
The goal is not perfection. The goal is a system that identifies risk early, bills accurately, follows up consistently, and protects working capital. Businesses that do this well gain more than faster payment. They gain steadier control.
Final Thoughts
Receivables are not simply numbers waiting to be collected. They are claims on future cash that must be managed with discipline. When collection systems improve, forecasting and operating decisions usually become more reliable.
Owners should treat accounts receivable mistakes as operational warning signs rather than minor administrative problems. Strong credit standards and prompt invoicing can prevent small delays from becoming larger liquidity problems. Clear terms, aging reviews, and consistent follow-up strengthen that protection.
Sources and Further Reading
- U.S. Small Business Administration: Manage Your Business and Finances
- FDIC: Money Smart for Small Business
Editor’s Note: This article was reviewed and refreshed in September 2026 for current financial-management guidance, clarity, and readability.
Financial Information Disclaimer: This content is for educational and general informational purposes only. It is not financial, legal, or tax advice. Business owners should consult qualified professionals before making financial decisions.
Amazon Affiliate Disclosure: As an Amazon Associate, Business Loan Press may earn from qualifying purchases. This does not change the price you pay.
Photo Credit: All images © Sloan Digital Publishing and licensed stock sources. Used with permission.