Interest-only business loan payments can leave more cash in your business today, but they do not make the debt smaller. During the interest-only period, your scheduled payment generally covers interest without reducing the principal you borrowed. That can be useful when the timing fits a real business need, but it can also move repayment pressure into the future.
Before accepting this structure, look beyond the attractive first payment. You need to know what happens to your balance, later payments, total borrowing cost, cash flow, and remaining debt at maturity. Those numbers tell you whether the interest-only period actually helps your business.
How Do Interest-Only Business Loan Payments Work?
With a typical amortizing business loan, each scheduled payment includes principal and interest. The principal portion gradually reduces the amount you owe. As that balance falls, interest is generally calculated against a smaller outstanding amount.
An interest-only period works differently. For a specified time, your required payments cover interest while scheduled principal repayment waits. If your business borrows $100,000 and makes only the required interest payments for a year, you can still owe $100,000 when that year ends.
You have made every required payment, but you have not reduced the original principal. That distinction explains both the short-term appeal and the longer-term risk of this loan structure.
Contractual Interest-Only Payments Are Not the Same as Payment Relief
There are two situations that can sound similar but should not be confused. A lender may structure a new loan with an interest-only period from the beginning. In that case, the lower initial payments are part of the original loan agreement.
A lender might also temporarily accept interest-only payments after an existing borrower develops financial trouble. That arrangement may be part of a modification, workout, forbearance, or another form of payment relief. The borrower is responding to a repayment problem rather than choosing the structure when taking out the loan.
This article focuses on the first situation. You are considering a loan that includes an interest-only period and deciding whether postponing principal repayment serves a useful business purpose. If you are already struggling with an existing loan, the questions and available options are different.
What Happens to Your Principal?
Your principal normally remains unchanged while you make only the scheduled interest payment. If you borrowed $100,000, you can reach the end of the interest-only period still owing the full $100,000. Your agreement may allow additional principal payments, but those are separate from the required interest-only payment.
This is why a lower monthly payment should not be confused with faster or cheaper repayment. You are paying for the use of the lender’s money while postponing repayment of the money itself. The principal still has to be dealt with later.
How Much Can the Initial Payment Drop?
A simplified example shows why an interest-only offer can look attractive. Suppose your business borrows $100,000 at a fixed 10% annual rate for five years. A fully amortizing 60-month loan would require a monthly principal-and-interest payment of about $2,125.
Now suppose the first 12 months require interest-only payments. At 10%, the simplified monthly interest payment would be about $833. Your business would keep roughly $1,292 more cash each month during that first year.
That extra room in the budget is real. However, the unpaid principal is also real. At the end of the year, the business still owes $100,000 and has only four years remaining in the original five-year term.
What Happens When the Interest-Only Period Ends?
Your loan agreement determines what happens next. One structure begins amortizing the remaining principal after the interest-only period. Because there is less time left to repay it, the required payment can increase substantially.
In our simplified example, amortizing the remaining $100,000 over the final 48 months at the same 10% rate would require a payment of about $2,536. The business moves from approximately $833 per month to approximately $2,536.
Another loan may not fully amortize before maturity. Instead, a significant principal balance may remain due at the end. That creates a balloon or payoff obligation that your business must be prepared to handle.
Actual loan terms can differ considerably. Variable rates, fees, payment frequency, amortization provisions, prepayment rules, and other contract terms can change these calculations. Ask the lender for the complete payment schedule before you sign.
Does the Interest-Only Period Increase Your Total Borrowing Cost?
It can increase total interest when principal stays outstanding longer. That difference may be easy to overlook when the initial payment is the number receiving most of your attention.
Return to the $100,000 example. At 10%, a fully amortizing five-year loan would generate approximately $27,482 in total interest. With 12 months of interest-only payments followed by four years of amortization, total interest would be approximately $31,740.
That is about $4,258 more interest under these simplified assumptions. In exchange, the business receives lower required payments during the first year. The relevant question is whether that temporary flexibility provides enough business value to justify the additional cost and later payment pressure.
Fees and other charges can widen the difference further. Compare the full cost of each financing offer rather than choosing by monthly payment alone.
When Can Lower Early Payments Genuinely Help Your Business?
An interest-only period can make sense when there is a predictable gap between spending money and receiving the economic benefit. For example, you might be opening another location that requires renovations, equipment, inventory, and hiring before normal sales begin.
Lower early payments could preserve working capital during that ramp-up period. A similar structure might help finance a project or asset that has a reasonable delay before it begins producing cash for the business.
The important word is predictable. You should be able to explain why cash flow is expected to improve and when that improvement should occur. Hope that “business will be better next year” is not the same as a supported projection.
The interest-only period is most useful when it bridges an identifiable timing gap. It becomes more concerning when postponing principal is the only reason the debt appears affordable.
What Will You Do With the Cash You Keep?
The lower initial payment has more value when the preserved cash has a specific job. Perhaps it supports inventory that will generate sales, protects a working-capital reserve during an expansion, or covers startup costs while a new location builds revenue.
Calculate how much cash the interest-only period will actually preserve. Then identify where that money will go and what benefit you reasonably expect it to produce. This turns “lower payments” into a business decision you can evaluate.
If the money simply disappears into routine expenses without improving the company’s position, the interest-only period may accomplish little. Your business reaches the end of the period with the same principal balance and a larger repayment obligation ahead.
Stress-Test the Payment That Comes Later
Do not test affordability using only the interest-only payment. Ask the lender for the expected payment after principal repayment begins, then put that larger number into your cash-flow forecast.
Could your business handle that payment with today’s revenue and expenses? If not, identify the specific change you expect before the higher payment begins. Test what happens if revenue arrives later than expected or falls short of your projection.
You can also compare the proposed debt with your broader borrowing capacity. BLP’s guide to how much business debt your company can safely afford provides a separate cash-flow test for that decision.
This exercise does not mean your business must already generate the future revenue today. It does require you to understand how dependent repayment is on assumptions that have not happened yet.
Do Not Overlook Maturity and Refinancing Risk
A loan that does not fully amortize can leave a substantial balance at maturity. Your business may need cash to pay it, proceeds from an asset sale, an extension from the lender, or new financing.
The Office of the Comptroller of the Currency warns that interest-only terms can improve current debt-service coverage while increasing balloon or full-repayment risk at maturity. OCC guidance also identifies interest-only loans among the lending structures particularly exposed to refinancing risk.
That does not mean an interest-only structure is inherently unsuitable. It means the end of the loan deserves as much attention as the beginning. You should know the expected maturity balance before accepting the financing.
Refinancing can be a reasonable future option, but it should not be treated as guaranteed. Interest rates, lending standards, collateral values, your financial performance, and credit conditions may all be different when the loan matures.
OCC guidance on commercial lending and refinance risk explains why loans with principal remaining at maturity deserve additional attention.
Compare the Structure With Ordinary Principal-and-Interest Repayment
Most conventional term-loan discussions assume that principal begins declining as scheduled payments are made. The U.S. Small Business Administration, for example, states that most 7(a) term loans use monthly principal-and-interest payments from business cash flow.
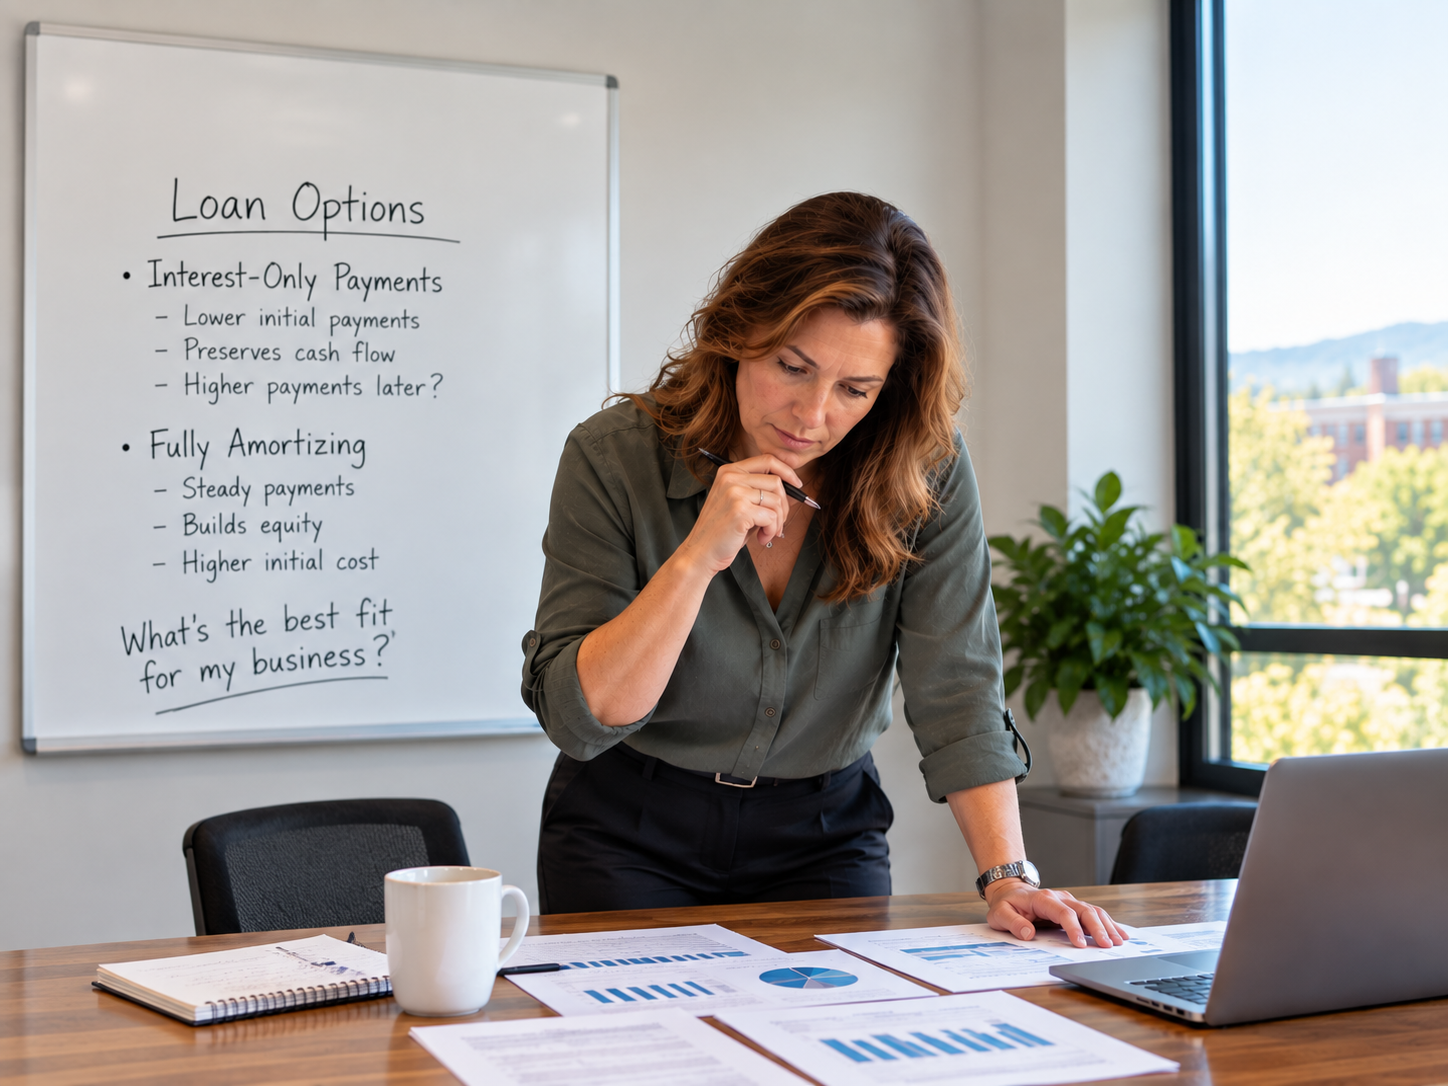
That does not make principal-and-interest repayment automatically preferable for every business situation. It gives you a useful baseline for comparison. You can see exactly what you gain by delaying principal and what that delay costs.
If you are comparing different financing structures, review BLP’s guide to different types of small business loans. Keep the comparison focused on the entire repayment structure, not simply the smallest opening payment.
Five Numbers You Should Know Before You Sign
You should be able to identify five numbers before deciding whether the interest-only feature genuinely helps your business. Together, they show what you receive now and what you commit yourself to later.
- Your required payment during the interest-only period.
- Your principal balance when that period ends.
- Your scheduled payment after principal repayment begins.
- Your estimated total interest and fees over the full loan term.
- Your remaining principal balance, if any, due at maturity.
Ask the lender for a written payment schedule rather than relying on a quoted opening payment. Confirm whether the rate is fixed or variable, whether you can make voluntary principal payments, and whether prepayment provisions apply.
Review the maturity date and any balloon payment carefully. If something in the agreement is unclear, ask for an explanation before signing. BLP’s guide on avoiding bad loan terms before you sign explains other contract provisions that deserve attention.
So, Is the Interest-Only Period Helping or Postponing Pressure?
The answer depends on what happens during the lower-payment period and whether your business can handle the obligation afterward. A useful interest-only structure solves a timing problem. It gives the business temporary flexibility while preserving a realistic path to principal repayment.
A risky structure can make an unaffordable loan look manageable because the first payment is artificially low. If the business cannot support the later payment or maturity balance, postponing principal has not solved that problem.
Before you sign, compare the cash you preserve with the additional interest you expect to pay. Then test the later payment against realistic projections and examine the maturity balance without assuming refinancing will be available.
The smallest payment is not necessarily the safest loan. What matters is whether your business can use the early flexibility productively and still manage the entire repayment path.
Amazon Affiliate Disclosure: As an Amazon Associate, Business Loan Press may earn from qualifying purchases. This does not change the price you pay.
Photo Credit: All images © Sloan Digital Publishing and licensed stock sources. Used with permission.
Disclaimer: This article is for general educational purposes only and does not constitute financial, legal, tax, accounting, or lending advice. Loan terms and repayment structures vary by lender and agreement. Review your loan documents and consult qualified professionals when appropriate.