Holiday cash flow planning should begin before seasonal spending starts draining your business account. Inventory, extra staffing, advertising, packaging, and shipping can require cash before seasonal sales replenish it. Regular expenses also continue while those extra costs accumulate. Strong holiday sales do not automatically prevent a cash shortage.
For small business owners, the challenge is not simply deciding how much to spend. Timing is equally important. You need to know when cash will leave and when you reasonably expect it to return. That knowledge can help you pursue seasonal opportunities without jeopardizing everyday operations.
Holiday Cash Flow Planning Starts With Timing
Revenue and available cash are not always the same thing. A sale can appear in your records before the money reaches your bank account. Meanwhile, suppliers, employees, landlords, lenders, and other creditors expect payment according to their schedules. Those timing differences can become more pronounced during a seasonal surge.
Consider a retailer that orders additional merchandise several weeks before the holidays. The supplier may require payment before much of that inventory sells. A service business can face similar pressure while waiting for customers to pay invoices. Mapping expected receipts and payments by date can expose these gaps early.
Our guide to the cash conversion cycle explains this timing problem in greater detail. It follows cash through inventory, sales, collections, and supplier payments. You do not need to repeat that entire calculation for holiday planning. You do need to recognize when business cash will be temporarily unavailable.
Identify Seasonal Spending Before It Starts
Separate unusual holiday expenses from costs you pay during an ordinary month. Seasonal costs might include inventory, temporary employees, overtime, advertising, packaging, shipping supplies, or extended operating hours. Your own list will depend on how your business changes during the holiday season. Estimating these costs early gives you time to adjust them.
Next, add expenses that continue regardless of holiday sales. Rent, utilities, insurance, existing debt payments, payroll, subscriptions, taxes, and essential vendor bills still require cash. Looking only at special holiday spending can make available cash appear more generous than it is. Your forecast needs both ordinary and seasonal obligations.
Do not assume every planned expense must occur at once. Some inventory orders may be staged if suppliers can replenish stock quickly. Advertising can sometimes increase after early promotions demonstrate worthwhile results. Preserving flexibility can reduce the amount of cash committed before demand becomes clearer.
Use Last Year’s Holiday Numbers Carefully
Previous holiday results can provide a useful starting point for this year’s forecast. Review prior sales, inventory purchases, staffing costs, advertising expenses, and other seasonal spending. Identify products that sold quickly and those that remained after demand slowed. Historical information is usually more useful than relying entirely on expectations.
Last year’s results are not a promise about this year. Supplier prices may have increased, customer demand may have shifted, and labor costs may differ. Your product mix or marketing strategy may also have changed. Adjust historical figures when current conditions give you a sound reason.
Pay attention to margins rather than sales totals alone. Higher revenue does not necessarily produce proportionally more available cash. Increased sales can require additional inventory, labor, shipping, and transaction costs. A strong seasonal sales number can hide disappointing cash results when costs rise too quickly.
Build More Than One Cash-Flow Scenario
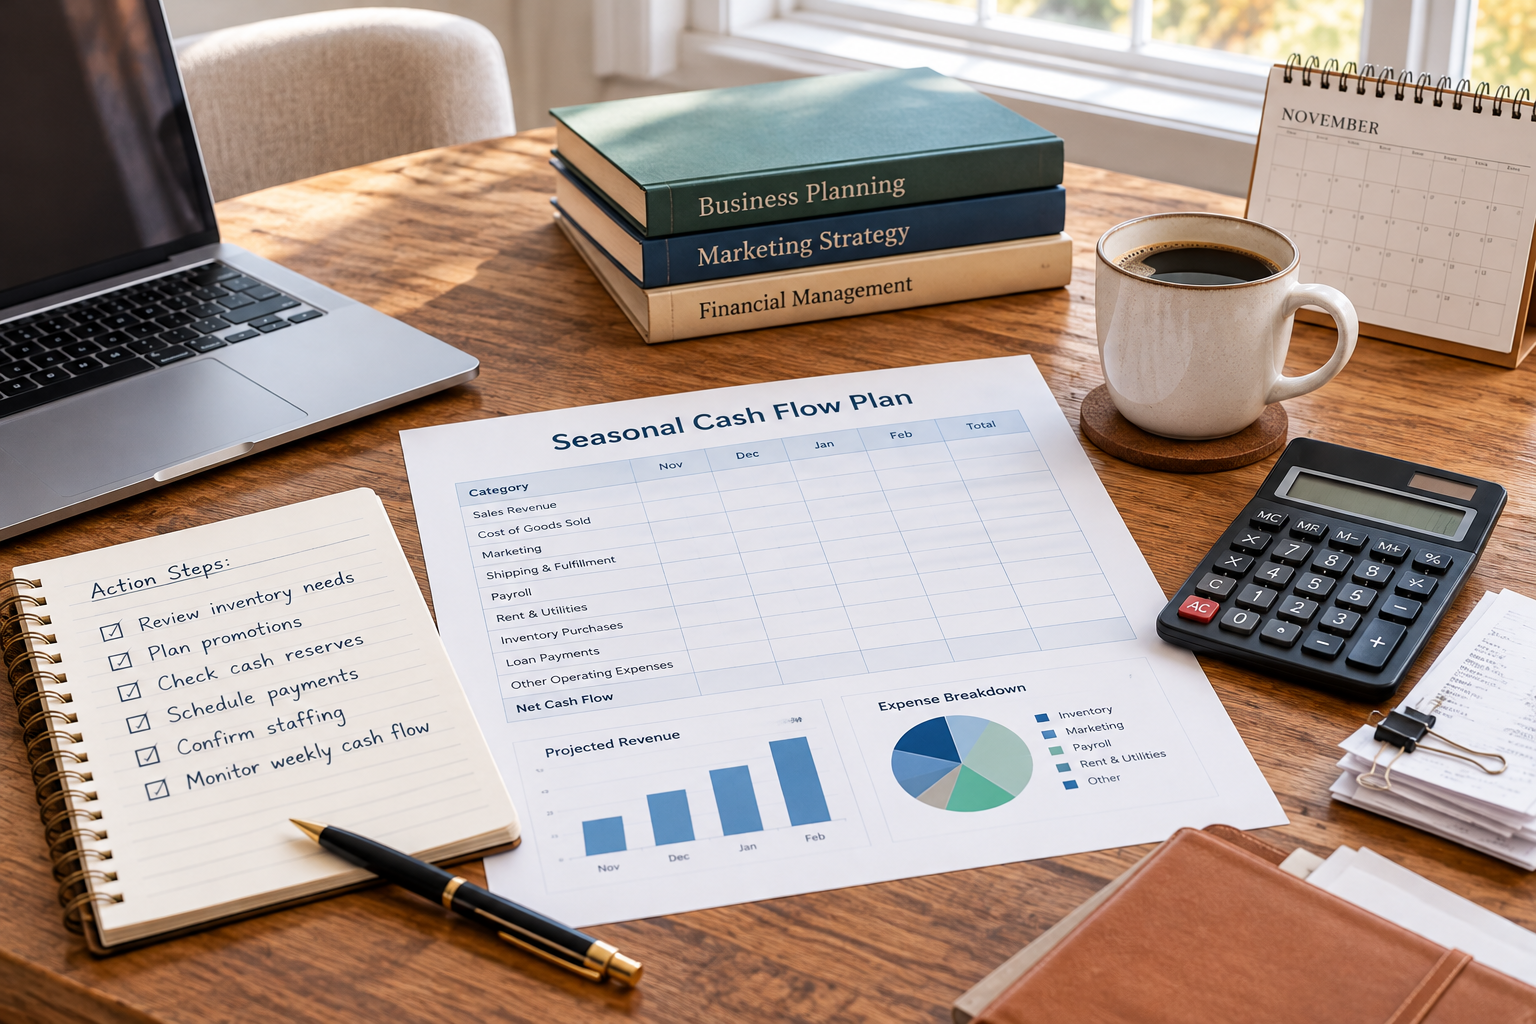
A single forecast can create more confidence than its assumptions deserve. Prepare an expected scenario and test what happens with stronger and weaker sales. The purpose is not to predict every possible outcome. It is to identify decisions that become dangerous when reasonable assumptions change.
In the weaker scenario, reduce expected sales or delay some customer payments. Then determine whether the business can still cover essential obligations. Include payroll, rent, taxes, debt payments, and critical vendor bills in that test. A plan that works only under ideal conditions deserves another look.
Strong sales can create cash pressure too. A retailer may need rapid inventory replenishment during an unexpectedly busy season. Another business may need additional labor, packaging, or shipping capacity. Those expenses can arrive before all related revenue reaches the bank.
Protect the Cash Your Business Already Needs
Before approving optional holiday spending, identify cash that already has a job. Payroll, rent, utilities, insurance, taxes, existing debt, and essential supplier payments deserve priority. Spending those funds because today’s bank balance looks healthy can create trouble later. Upcoming obligations belong in the decision before discretionary spending begins.
There is no single reserve amount that suits every small business. Our guide to building a small business cash reserve examines that question in detail. For this holiday forecast, concentrate on protecting known obligations and a reasonable operating cushion. Do not invent a universal percentage simply because it sounds reassuring.
This creates a useful test for proposed holiday spending. Ask what your cash balance will look like after the purchase and upcoming obligations. Then repeat the calculation using your weaker-sales scenario. An expense becomes less attractive when it leaves essential bills dependent on optimistic sales.
Watch Holiday Inventory Closely
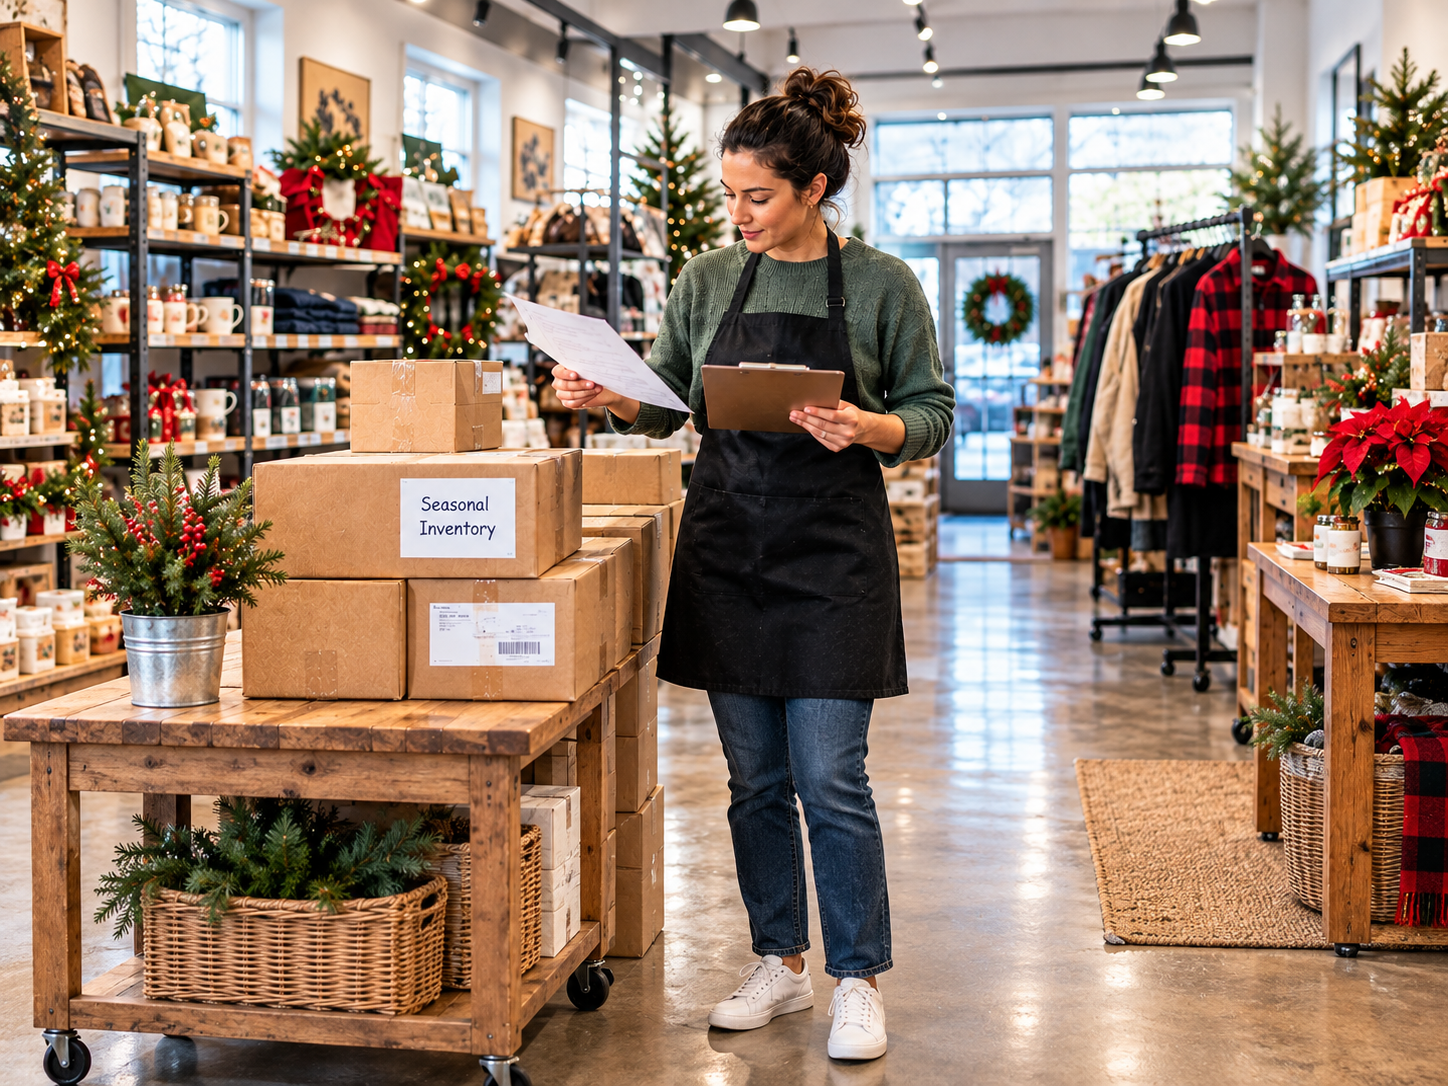
Inventory can consume substantial cash before holiday selling reaches its peak. Ordering too little can mean missed sales and disappointed customers. Ordering too much can leave money trapped in merchandise after seasonal demand fades. The goal is to balance availability against the financial cost of excess stock.
Review prior sales by product when that information is available. Identify items that moved quickly and those that required later discounts. Current orders, customer inquiries, and supplier lead times can provide additional information. Avoid treating every product as though it carries the same demand risk.
The SCORE Association recommends using historical sales data to forecast holiday inventory needs rather than relying entirely on guesswork. Previous results cannot predict demand perfectly, but they provide useful evidence for purchasing decisions.
Supplier payment terms also affect the forecast. Inventory paid for immediately creates different pressure from purchases with later payment terms. Record when payment is actually due, not merely the purchase amount. This shows when an inventory decision will affect available cash.
Look Beyond December 31
Holiday cash flow planning should extend into January. Bills created during the holiday rush may arrive after the season ends. Customer returns and refunds can reduce cash receipts after December sales are recorded. Sales may also slow while ordinary operating expenses continue.
Review January obligations while making November and December spending decisions. Include vendor invoices, payroll, rent, debt payments, and other predictable costs. Tax obligations may also require attention depending on your circumstances. The IRS provides current guidance on estimated tax obligations for businesses and self-employed taxpayers.
This longer view can change an apparently affordable holiday decision. Cash that looks available in December may already be needed for January obligations. Extending the forecast by several weeks makes that conflict easier to see. It also discourages spending a temporary year-end cash balance too freely.
Decide Whether a Cash Gap Is Temporary or Structural
Your forecast may reveal a period when available cash falls below what the business needs. Before seeking financing, determine why the gap exists. A temporary timing problem differs from an ongoing inability to generate enough cash. That distinction should influence whether borrowing is appropriate.
A temporary gap might occur when reliable receivables arrive shortly after major expenses become due. Seasonal inventory can create another temporary need when historical demand provides reasonable support. Repeated shortages during ordinary operations can indicate a deeper financial problem. New debt may postpone that problem rather than correct it.
Our year-end business planning before borrowing guide provides a broader borrowing review. For this decision, identify the shortage, its expected duration, and the likely repayment source. Also determine whether delaying or reducing spending could close part of the gap. Financing should address a defined need rather than an undefined desire for extra cash.
Consider Financing Only After Identifying the Gap
Seasonal financing can sometimes support a legitimate short-term working-capital need. However, the repayment obligation remains after the holiday rush ends. Estimate the amount actually required instead of automatically borrowing the maximum available. Test repayment under the weaker-sales scenario before committing.
Compare financing by total cost, fees, repayment schedule, and cash-flow impact. Be cautious when costs are difficult to understand or payments begin immediately. Frequent withdrawals can create additional pressure during an already demanding season. Fast approval alone does not make financing affordable.
Holiday deadlines should not rush a financing decision. Read the agreement and understand its obligations before signing. Our guide to avoiding predatory lenders explains warning signs and troublesome loan terms. Seasonal urgency is a reason for greater scrutiny, not less.
Perform a Practical Pre-Holiday Cash Check
Before approving a significant seasonal expense, identify its amount and payment date. Compare that payment with the cash expected to be available then. Next, identify essential obligations due before the business should recover the money. This provides a clearer picture than checking today’s bank balance.
Repeat the calculation using the weaker scenario from your forecast. Determine whether the expense would push available cash below your protected level. If it does, reconsider the amount, timing, or source of funds. Making that adjustment early usually leaves more options available.
Continue updating the forecast as the season develops. Actual sales may differ from expectations, while expenses may rise or fall. New information should influence later spending decisions. A forecast provides the most value when it remains an active management tool.
Plan for the Holiday Opportunity Without Creating a January Problem
The purpose of holiday cash flow planning is not to minimize every seasonal expense. Thoughtful spending can help a business capture legitimate opportunities during an important sales period. The goal is to pursue those opportunities without sacrificing the liquidity needed for normal operations. That requires attention to timing as well as expected revenue.
Forecast incoming and outgoing cash before making large seasonal commitments. Protect essential obligations, test weaker assumptions, and watch inventory carefully. Consider financing only after identifying the size and duration of a genuine cash gap. A successful holiday season should strengthen the business instead of leaving January to pay for December.
Sources: SCORE, “How to Avoid Inventory Shortfall This Holiday Season”; U.S. Small Business Administration, “Check Your Business KPIs Before the Holiday Season Starts”; Internal Revenue Service, “Estimated Taxes”.
Business Loan Press Disclaimer: This article is for general educational and informational purposes only. It does not constitute financial, legal, tax, or lending advice. Business owners should evaluate their individual circumstances and consult qualified professionals when appropriate.
Amazon Affiliate Disclosure: As an Amazon Associate, we may earn from qualifying purchases without any additional cost to you.
Photo Credit: All images © Sloan Digital Publishing and licensed stock sources. Used with permission.