Short-term business loan risks can be easy to underestimate when a company is caught in a cash flow squeeze. A tax bill is due, equipment fails, inventory has to be ordered, or an important customer pays late. When the problem is urgent, getting approved quickly can feel more important than almost anything else.
The greatest danger is not always the amount borrowed or even the stated cost of financing. Repayment frequency, loan structure, cash flow timing, and the reason the business needs money can determine whether short-term financing solves a problem or simply moves it a few weeks down the road.
Short-term financing is not automatically a bad choice. Used for a defined need with a realistic repayment source, it can be useful. Trouble begins when an owner evaluates the financing primarily by how quickly the money will arrive instead of what happens to the business after repayment begins.
Why short-term financing attracts capable business owners
Most owners who seek fast financing are not being reckless. They are responding to pressure. A seasonal inventory purchase may have to happen before revenue arrives. A valuable piece of equipment may need immediate repair. Receivables may be healthy overall but poorly timed against payroll or supplier payments.
Speed has legitimate value in situations like these. The problem is that urgency compresses decision time. Financing that can be approved quickly may receive less scrutiny than a conventional loan requiring a longer application process, even though the faster obligation may put substantially more pressure on day-to-day cash flow.
That distinction is especially important when comparing banks, credit unions, online lenders, lines of credit, short-term loans, and other forms of business financing. Small businesses use all of these sources, but owners should compare more than approval speed when deciding which option fits their situation.
A fast approval therefore answers only one question: Can you get the money? It does not answer the more important question: Can the business comfortably carry the obligation?
Short-term business loan risks often come from repayment structure
Business owners naturally look at interest rates and total borrowing amounts, but the structure of repayment can be just as important. A payment may look affordable by itself but become difficult when frequent withdrawals hit at the wrong point in the company’s cash cycle.
A business does not earn and spend money in a perfectly straight line. Revenue may arrive heavily at the end of the month, after a project is completed, or during particular seasons. Payroll, rent, insurance, inventory, taxes, and vendor obligations follow their own schedules. Financing that ignores those patterns can create a liquidity problem even in a profitable company.
Daily and weekly payments can change the equation
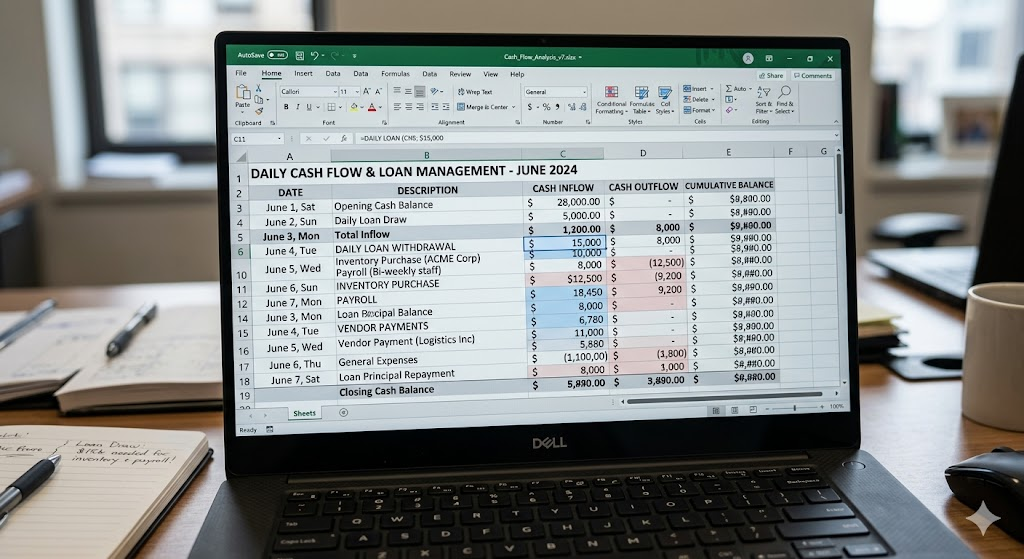
Traditional monthly payments are relatively easy to incorporate into a budget. Daily or weekly withdrawals can behave differently. Each individual withdrawal may look smaller, but frequent deductions continually remove cash that otherwise could absorb a delayed receivable, unexpected repair, inventory opportunity, or temporary sales decline.
This does not mean that every financing product with frequent payments is unsuitable. It means the owner needs to model the actual withdrawal schedule against realistic cash inflows rather than looking only at the advertised payment amount.
For example, a business that receives most customer payments twice a month may experience considerable strain from withdrawals occurring every business day. The problem is not necessarily profitability. It is timing.
Do not confuse every short-term product with a conventional business loan
Terminology can make comparison harder. A merchant cash advance, for example, does not use the same structure as a conventional term loan. The business receives an advance and agrees to repay a larger amount, sometimes expressed through a factor or payback rate. The provider may collect repayment as a percentage of future revenue or through fixed daily withdrawals.
That distinction is important because a factor rate should not be casually read as though it were an annual percentage rate. Owners comparing offers should identify exactly what kind of financing they are considering, calculate the total dollars that must be repaid, identify all fees, and understand how quickly that repayment will occur.
A financing offer becomes much easier to evaluate when the owner stops asking, “What is the payment?” and instead asks, “How much cash will leave this business, how often will it leave, and how much will this financing cost from beginning to end?”
How short-term business loan risks affect daily operations
One of the most important short-term business loan risks is the way repayment pressure can spread beyond the original expense. Suppose financing successfully pays for an urgent inventory order. If aggressive repayments then leave too little cash for payroll, marketing, taxes, or the next inventory cycle, the original problem has been solved at the expense of creating another one.
The effects often appear gradually. An owner postpones a purchase for a week, pays a supplier later than usual, cuts an advertising campaign, or delays maintenance. Each decision may seem harmless by itself. Together, they can make the business less resilient and force management to spend more time juggling cash than running the company.
Receivables deserve particular attention. A company can show a profit on paper while waiting weeks for customers to pay. If loan withdrawals continue while those receivables remain outstanding, the financing may amplify an existing cash flow weakness.
Before adding debt, examine whether collections are contributing to the shortage. Our guide to accounts receivable mistakes that hurt cash flow explains how slow collections and weak receivables practices can quietly reduce available cash.
Repeated borrowing can create a different problem. When a company becomes accustomed to filling routine cash shortages with financing, access to credit can begin replacing improvements that are needed inside the business. Our discussion of the business financing dependence cycle looks more closely at how that pattern develops.
When short-term borrowing points to a deeper problem
Some short-term business loan risks come from the financing itself, while others reveal problems that already exist inside the company. A temporary cash shortage and a structurally weak business are not the same thing. Short-term financing works better for a temporary mismatch when the source of repayment is reasonably visible. It cannot permanently repair inadequate margins, chronic overspending, poor pricing, uncontrolled inventory, or recurring operating losses.
One warning sign is borrowing repeatedly to pay ordinary expenses. Payroll, rent, utilities, and normal supplier bills are predictable costs of operating a business. If new financing is routinely required to cover them, the underlying issue deserves attention before another loan is added.
Another warning appears when repayment depends on everything going right. A loan may look affordable if sales rise 20 percent, every major customer pays on time, and no unexpected expense occurs. That is not much of a safety margin. A sound borrowing decision should work under less favorable conditions as well as the owner’s expected forecast.
Customer concentration can make the situation even more fragile. If one customer represents a large share of revenue, a late payment or lost account can quickly undermine projections that originally supported the loan. Financing decisions should reflect that exposure rather than assuming historical revenue will continue uninterrupted.
How financing dependency can begin
Dependency rarely announces itself with a dramatic financial crisis. One loan may close a legitimate gap. The repayment then reduces available cash, so the owner turns to another financing product several months later. Eventually, management begins planning around the availability of outside money rather than rebuilding adequate working capital inside the company.
The business may still look active and successful. Employees are working, customers are buying, and revenue continues to enter the bank account. Internally, however, increasingly large portions of incoming cash may already have a destination before management can use them.
Borrowing to repay earlier borrowing deserves particular scrutiny. Refinancing can sometimes improve an unhealthy debt structure, but repeatedly adding expensive debt merely to stay ahead of existing payments is different. At that point, an owner should examine the company’s margins, expenses, receivables, inventory, and overall debt load before assuming another infusion of cash will solve the problem.
Seven questions to answer before accepting short-term financing
- What exact problem will this money solve? “We need cash” is not specific enough. Identify the expense, amount, timing, and expected business benefit.
- What is the total dollar cost? Determine how much money the business receives and exactly how much it must repay, including origination charges and other required fees.
- How often will payments occur? Monthly, weekly, and daily repayment schedules can have very different effects on working capital.
- What cash flow will repay the financing? Identify a realistic repayment source rather than relying on a general expectation that future sales will improve.
- What happens if revenue falls or receivables arrive late? Stress-test the obligation. A financing arrangement that works only under ideal conditions may be too aggressive.
- Are there restrictions or costs associated with early repayment? Do not assume that paying financing off early automatically reduces the cost. Read the agreement and ask the lender to explain the provision in writing.
- Is there a less disruptive way to solve the problem? Compare the offer with a line of credit, conventional term loan, SBA-backed financing where appropriate, vendor negotiations, receivables improvements, expense reductions, or simply delaying a nonessential expenditure.
Compare financing by cash flow impact, not approval speed
One of the best ways to reduce short-term business loan risks is to compare offers by their effect on cash flow rather than by which lender can fund first. Put competing offers side by side and compare the amount received, total repayment, fees, payment frequency, maturity, collateral or guarantee requirements, prepayment provisions, and the effect of each payment schedule on working capital.
The U.S. Small Business Administration encourages prospective borrowers to compare rates, terms, fees, cash-flow requirements, and other features when talking with lenders. SBA-backed financing will not fit every borrower or every urgent situation, but the comparison process illustrates why financing should be evaluated as a complete structure rather than simply by how quickly money can arrive.
For eligible businesses, SBA’s 7(a) program can support both short- and long-term working capital, among other permitted uses. Qualification and timing vary, so an SBA-backed loan should not be treated as an emergency substitute that will necessarily close as quickly as short-term online financing.
Owners who want to investigate that option can review the SBA 7(a) loan program and SBA Lender Match directly.
Alternatives to consider before taking fast money
Sometimes the best alternative is another type of financing. A business line of credit, for example, may provide flexibility when a company regularly experiences timing gaps but does not need to borrow a fixed lump sum. A conventional term loan may be preferable when the need is predictable and the business has enough time to complete a more traditional underwriting process.
In other situations, the answer may not be another loan at all. Faster receivables collection, lower inventory levels, renegotiated supplier terms, delayed discretionary spending, or a carefully planned expense reduction can release cash without adding another repayment obligation.
The source of the shortage should drive the solution. If $30,000 is needed because a profitable seasonal opportunity will generate $60,000 in well-supported additional gross profit, financing deserves serious analysis. If the same $30,000 is needed because the company loses money during normal operations every month, borrowing addresses a very different problem.
That distinction is easy to miss when money is urgently needed. It is also one of the most valuable distinctions an owner can make.
When a short-term business loan can make sense
Short-term financing can be reasonable when the need is specific, temporary, and supported by a credible repayment source. A company might need to bridge a well-documented receivable, replace essential equipment, or purchase inventory for a predictable seasonal sales period. In those circumstances, speed may have enough economic value to justify paying more for financing.
Short-term business loan risks are easier to manage when the expected benefit comfortably exceeds the financing cost and repayment leaves enough liquidity for normal operations. The business should also have a fallback plan if the expected cash arrives later than anticipated.
That is a much stronger standard than simply asking whether the lender will approve the application.
Good financing should leave the business stronger
Fast access to capital can be valuable, and short-term lending has legitimate uses. The mistake is treating speed as evidence that the financing itself is a good deal. Approval solves the lender-access question; it does not solve the cash-flow question.
The most important short-term business loan risks become easier to recognize when owners examine repayment frequency, total dollars repaid, cash flow timing, alternative financing, and the underlying reason the money is needed. A loan should support a workable business plan rather than become the plan.
Before signing, run the numbers under both expected and difficult conditions. If the business can repay the obligation while continuing to meet payroll, pay suppliers, maintain inventory, handle taxes, and absorb a reasonable surprise, the financing may deserve consideration. If repayment leaves virtually no room for error, fast money may solve today’s problem by creating tomorrow’s.
Financial Information Disclaimer
This article is provided for general educational purposes only. It does not constitute financial, legal, tax, accounting, or lending advice. Financing terms, eligibility requirements, costs, and laws can change. Business owners should review financing decisions and contractual obligations with appropriately qualified financial, legal, accounting, or tax professionals before acting.
Editor’s Note: This article was updated in October 2026.
Amazon Affiliate Disclosure: As an Amazon Associate, we may earn from qualifying purchases without any additional cost to you.
Photo Credit: All images © Sloan Digital Publishing and licensed stock sources. Used with permission.