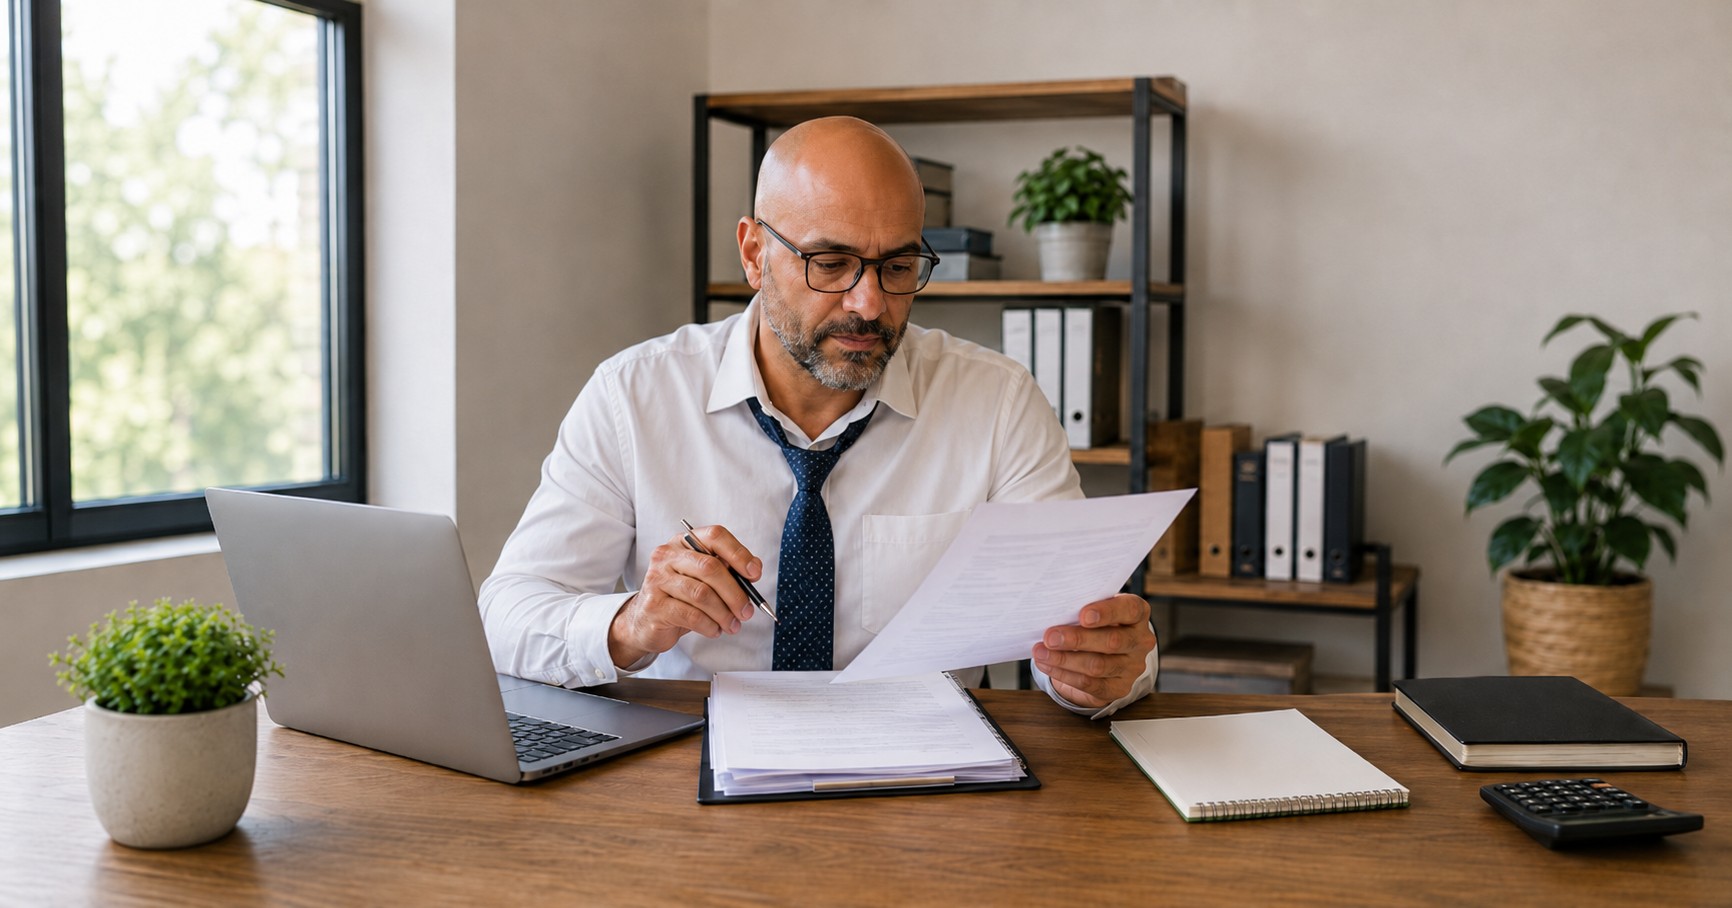
Are you wondering whether you qualify for a business loan? Perhaps your business needs equipment, additional inventory, or help managing seasonal expenses. You may also be concerned about taking on another monthly payment. Before approaching a lender, you deserve a clear picture of your options.
Qualifying is important, but approval should not be your only goal. You also need financing your business can comfortably repay. A loan that looks attractive today could create pressure during a slower month. Careful preparation helps you recognize that risk before signing.
These ten questions will help you examine your business from both perspectives. You will consider what lenders typically review and what your business can realistically afford. You will also identify documents to gather and warning signs to address. The goal is a sound borrowing decision, not simply an approval.
What Does It Mean to Qualify for a Business Loan?
To qualify for a business loan, you generally need to demonstrate your ability to repay it. Lenders may examine revenue, cash flow, credit history, business experience, and available collateral. They also consider the requested amount and intended use. Requirements vary among lenders and financing programs.
Your business might qualify with one lender but not another. Some lenders prefer established businesses with several years of financial records. Others consider newer businesses, although their financing may carry additional costs. Compare the requirements before assuming that one rejection closes every option.
Start by reviewing our guide to business loan requirements. It can help you understand the information lenders may request. Then use the following questions to evaluate your own readiness.
Question 1: Why Do You Need the Loan?
Begin with the problem you want the loan to solve. Perhaps your bakery needs another oven to meet existing demand. Maybe your landscaping business needs equipment before its busiest season. A specific purpose makes it easier to estimate the amount needed.
Write down what you intend to purchase or finance. Include related costs, such as installation, delivery, training, or initial supplies. Separate necessary expenses from purchases that could wait. This exercise may reveal that you need less financing than expected.
Next, consider how the expense will benefit your business. Will it increase production, replace unreliable equipment, or help manage predictable seasonal expenses? Estimate the benefit conservatively rather than assuming every improvement will increase sales. Borrowing should support a realistic plan.
Question 2: Has Your Business Been Operating Long Enough?
Some lenders prefer businesses with at least two years of operating history. That is a lender preference, not a universal qualification rule. Newer businesses may have options through different lenders or programs. Your circumstances determine which opportunities deserve consideration.
If your business is relatively new, gather evidence of its progress. Prepare sales records, bank statements, financial reports, and relevant contracts. Your industry experience may also help explain your ability to operate successfully. Do not exaggerate projections to compensate for a short operating history.
Ask prospective lenders about their minimum operating-history requirements before submitting applications. This can save time and unnecessary credit inquiries. If you fall short, ask what would strengthen a future application. Waiting may be more useful than accepting unsuitable financing.
Question 3: Can Your Cash Flow Support Another Payment?
This may be the most important question you ask yourself. Strong sales do not always mean money is available when bills arrive. Customers may pay late, while payroll and rent remain due. A new loan payment adds another fixed obligation.
Review your cash flow over several recent months. Subtract operating expenses, taxes, existing debt payments, and other necessary commitments. Then estimate the proposed loan payment using realistic financing terms. Look especially closely at months when business is slower.
Consider a simple example involving a proposed monthly payment of $900. If your business regularly has only $1,100 available, that leaves little room for surprises. A delayed customer payment could quickly create pressure. The lender’s approval would not eliminate that risk.
Our article on cash flow before a business loan explains this review in greater detail. Use your actual financial records rather than optimistic estimates. If repayment looks uncertain, reconsider the amount or timing.
Question 4: Are Your Financial Records Ready?
You do not need an elaborate office to maintain useful records. You do need accurate information about money entering and leaving your business. Incomplete records can delay an application or make repayment ability difficult to demonstrate. They can also hide financial problems from you.
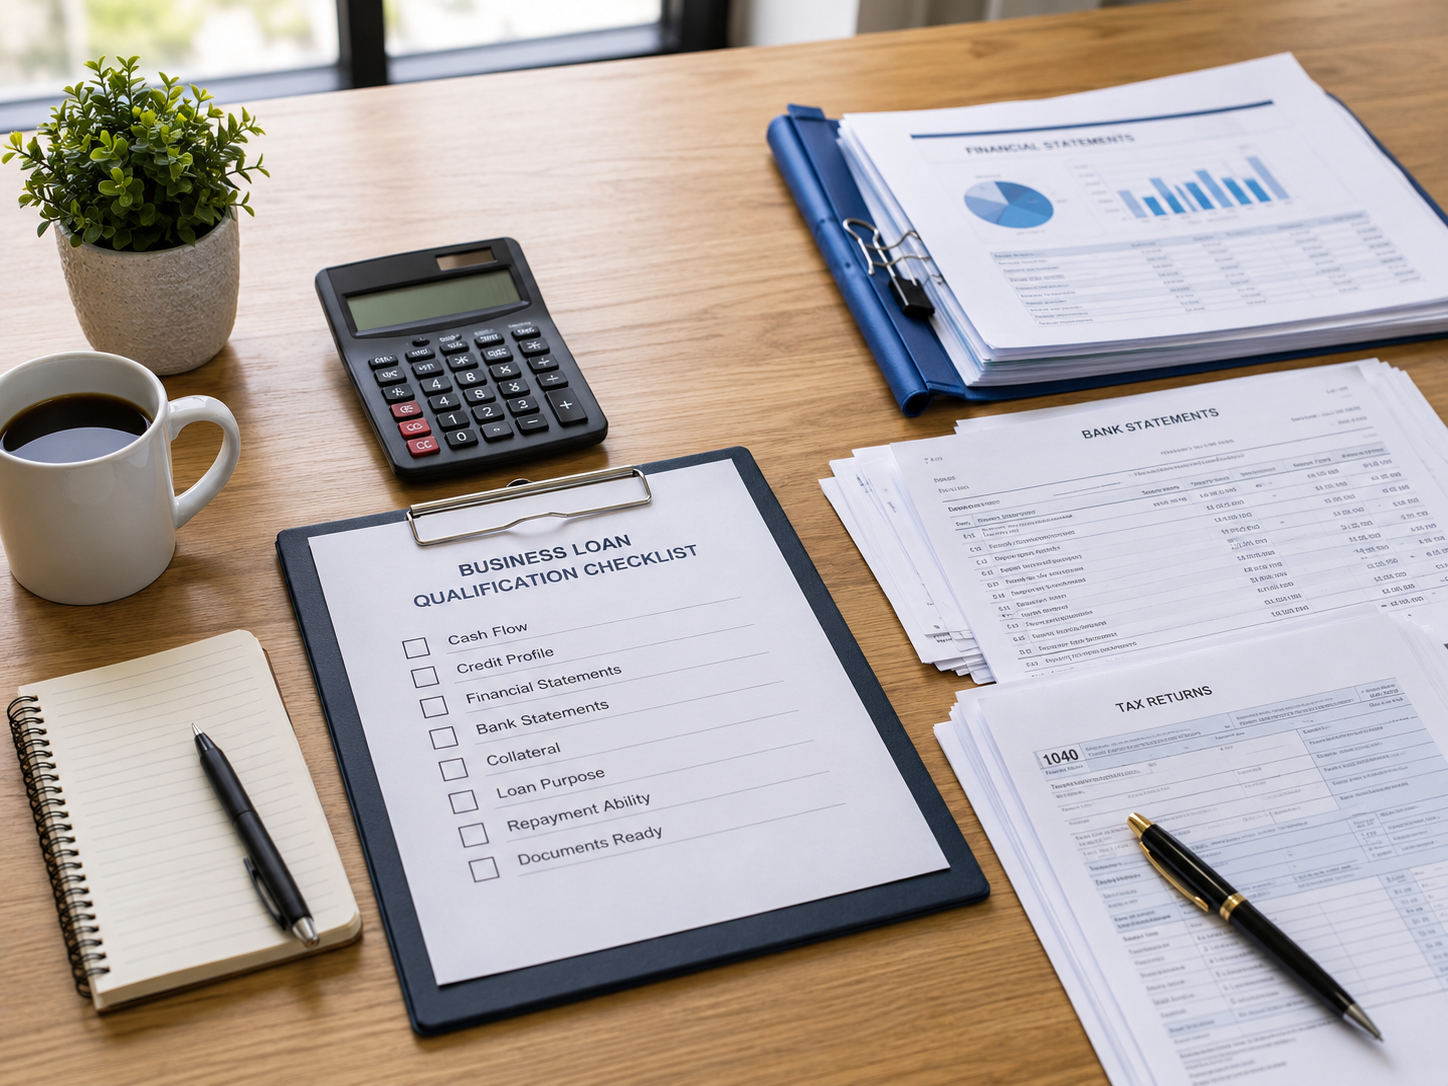
Gather recent bank statements, tax returns, income statements, and balance sheets. Include existing debt information and ownership documents when requested. Compare the figures for inconsistencies that might require explanation. Your lender will provide its specific documentation requirements.
If bookkeeping has fallen behind, address that before applying. You may need assistance from a bookkeeper or accountant. The investment could be more useful than rushing into financing. Reliable records help you make better decisions even without a loan.
Question 5: What Does Your Credit History Show?
Your credit history may influence approval, interest rates, and available loan terms. Lenders sometimes examine both business and personal credit. This is particularly relevant when a business has limited operating history. Requirements differ, so ask which reports the lender reviews.
Check your credit information before applying. Look for incorrect balances, unfamiliar accounts, and reporting errors. Address outstanding problems where possible and document resolved issues. Avoid paying for unnecessary credit services that promise guaranteed approval.
Credit problems do not always mean financing is impossible. However, they may reduce your choices or increase borrowing costs. Our guide to improving credit before applying offers additional preparation steps. Give yourself time to make meaningful improvements.
Question 6: What Could You Risk Through Collateral or a Personal Guarantee?
Before accepting financing, understand what the lender could claim if repayment fails. Collateral may include equipment, inventory, vehicles, or other assets. A personal guarantee can create responsibility beyond the business itself. These are different protections with potentially serious consequences.
Ask which assets would secure the loan. Find out whether the lender requires a personal guarantee. Review any lien provisions and the circumstances that could trigger collection. Consider obtaining qualified legal advice before signing unfamiliar agreements.
Our articles explain collateral in small business loans and personal guarantees in greater detail. Read these provisions before making a commitment. Protecting your business also means understanding your personal exposure.
Question 7: What Do Your Bank Statements Reveal?
Your bank statements show how your business handles money over time. Frequent overdrafts, returned payments, or unexplained transfers may concern a lender. They can also reveal problems worth addressing before borrowing. Review several months rather than relying on one strong period.
Look for patterns in deposits and withdrawals. Are expenses increasing faster than revenue? Do large customer payments arrive after major bills become due? Are personal and business transactions mixed together?
If your statements reveal problems, identify their causes. Some issues may reflect seasonal operations rather than poor management. Others may require changes to spending or payment collection. Prepare explanations supported by accurate records.
Question 8: Does the Loan Program Fit Your Business?
Not every loan product suits every business need. Equipment financing may fit a machinery purchase. A line of credit may better address recurring short-term cash gaps. A term loan may suit a defined investment with predictable repayment.
Compare eligibility requirements before submitting applications. Ask about minimum revenue, operating history, credit expectations, and acceptable uses. Also review fees, repayment schedules, and security requirements. A quick approval is not automatically the best offer.
The SBA 7(a) program supports several eligible business financing purposes. Its rules include creditworthiness and reasonable repayment ability. You apply through participating lenders, which review your circumstances. The SBA also offers Lender Match to help identify potential lenders.
Question 9: Are You Borrowing the Right Amount?
It can be tempting to borrow extra money while financing is available. However, a larger loan generally creates a larger repayment obligation. Borrowing too little can also leave an important project unfinished. Your goal is an amount supported by a realistic plan.
Prepare an itemized estimate of the expenses being financed. Include necessary related costs and an appropriate contingency when justified. Compare that total with your available cash and repayment capacity. Avoid treating the lender’s maximum offer as your target.
Request estimates showing the full borrowing cost. Compare interest rates, fees, repayment periods, and payment frequency. Ask whether rates can change and whether prepayment penalties apply. Focus on the total obligation, not only the advertised monthly payment.
Question 10: Are You Prepared to Apply Without Rushing?
Gathering documents before contacting lenders can make the process easier. Start with a clear description of your business and loan purpose. Prepare financial records, ownership information, and existing debt details. Add supporting estimates or contracts when relevant.
Keep the documents organized in a secure location. An accordion file organizer may help if you maintain paper records. The Sooez 13-Pocket Accordion File Organizer is one optional choice. You do not need to purchase one to qualify for financing.
Electronic folders can work just as well when properly protected. Avoid sending confidential financial records through insecure channels. Use the lender’s approved submission process for sensitive documents. Organization is valuable because it improves accuracy and reduces delays.
Before applying, review how to apply for a small business loan safely. Prepare questions about fees, guarantees, repayment terms, and application requirements. Take enough time to understand the answers.
Signs You May Be Ready to Apply
You can explain exactly why your business needs financing. You have calculated a realistic amount and identified how repayment would work. Your financial records are current and reasonably consistent. You understand the risks associated with the proposed loan.
You have also compared financing options rather than accepting the first offer. Your business can manage the proposed payment during slower periods. You know which documents the lender requires. These are useful indicators of preparation, although approval remains uncertain.
Signs You May Need More Preparation
Perhaps your financial records are incomplete or your cash flow is unpredictable. Maybe existing debt already consumes most available funds. You may also be uncertain about the loan’s purpose. These concerns deserve attention before adding another obligation.
Be especially cautious when financing would cover repeated operating losses. Borrowing can provide temporary relief without correcting the underlying problem. A cash flow review may reveal better alternatives. Sometimes reducing expenses or adjusting payment terms is the safer first step.
Pressure from a lender is another warning sign. Do not sign agreements you have not read or understood. Ask for complete terms and enough time to compare offers. A legitimate financing decision should withstand careful review.
Business Loan Qualification Quick-Check
Use this checklist before submitting an application. Each item addresses a practical question about readiness. You may discover that some areas need additional work. That knowledge can prevent an expensive decision made too quickly.
- Can you explain exactly why you need the financing?
- Have you calculated the amount required?
- Can your business afford payments during slower months?
- Are your financial statements current and accurate?
- Have you organized the documents your lender requests?
- Have you reviewed your business and personal credit information?
- Do you understand collateral and personal guarantee requirements?
- Can you explain unusual banking activity?
- Have you compared loan products, costs, and repayment terms?
- Do you know what could happen if repayment becomes difficult?
Final Thoughts on Qualifying for a Business Loan
You may qualify for a business loan without finding one that truly fits your business. Approval is only one part of a responsible financing decision. Your ability to repay comfortably deserves equal attention. So does the risk you accept through guarantees and collateral.
Begin with your numbers, not the lender’s maximum offer. Choose financing that supports a specific business purpose. If the figures suggest waiting, give yourself permission to prepare further. A sound decision is more valuable than a hurried approval.
Helpful Resources
- U.S. Small Business Administration: Business Loan Programs
- U.S. Small Business Administration: Lender Match
- Internal Revenue Service: Business Recordkeeping
- Business Loan Requirements: What Lenders Usually Want to See
Photo Credit: All images © Sloan Digital Publishing and licensed stock sources. Used with permission.
Amazon Affiliate Disclosure: As an Amazon Associate, we may earn from qualifying purchases without any additional cost to you.
Editor’s Note: This article was updated in November 2026.
Disclaimer: This article is for general educational purposes only and is not financial, legal, tax, lending, or investment advice. Business owners should review loan documents carefully and consult qualified professionals before making borrowing decisions.


türkçe izle
Thanks for sharing, this is a fantastic post. Much thanks again. Really Great. Paule Kinny Gianni
720p izle
Way cool! Some extremely valid points! I appreciate you penning this write-up and also the rest of the site is also very good. Rana Bink Petite
dizi
I got what you intend,bookmarked, very decent site. Truda Lalo Howey
Susan Sloan
Thank you,
Susan Sloan
Hi Truda,
Thank you for your interest in Business Loan Press! We don’t have a subscription option set up yet to offer you, but we’re working on it. In the meantime, please check back here regularly for new updates.
anime
Hi, I wish for to subscribe for this blog to get latest updates, thus where can i do it please help out. Lilia Maury Moia
Susan Sloan
Hi Lilia,
Thank you for your interest in Business Loan Press! We don’t have a subscription option set up yet, but we’re working on it. In the meantime, you can check back here regularly for new updates. I’ll be sure to share once our subscription feature goes live.