 Thanksgiving cash flow planning can help your small business enjoy a successful holiday weekend without unexpected financial pressure. Strong sales are encouraging, but they do not always mean money is immediately available. Payroll, supplier bills, and other expenses may arrive before your holiday sales reach the bank.
This timing difference can create problems even when your business is profitable. Customers may pay by card, while deposits arrive several days later. Meanwhile, scheduled withdrawals continue regardless of how busy your business becomes.
Retailers are not the only businesses affected. Restaurants, online sellers, service providers, and other small employers may face unusual holiday expenses. Preparing early gives you more control over those financial demands.
Start With the Cash You Can Actually Use
Before making holiday spending decisions, review your business bank balance. Subtract outstanding checks, scheduled withdrawals, and other committed payments. The remaining amount provides a more realistic picture of your available cash.
Next, list the payments you expect to receive before and after Thanksgiving. Separate confirmed deposits from projected sales and unpaid invoices. Do not treat expected revenue as money already available for spending.
Pay particular attention to overdue customer payments. A large unpaid invoice could affect your ability to meet payroll or pay suppliers. Contact customers professionally before a delayed payment becomes an urgent problem.
Thanksgiving Cash Flow Planning: Build a Simple Forecast
You do not need expensive software to create a useful cash-flow forecast. A spreadsheet or carefully maintained worksheet can help you organize expected receipts and expenses. The most important detail is when money will actually become available.
Thanksgiving cash flow planning works best when you compare expected deposits with their likely arrival dates. Begin with your available cash balance and add confirmed incoming payments. Then subtract obligations due during each period.
A simple accounting ledger can help organize incoming payments, expenses, and account balances. If you prefer handwritten records, an accounting ledger book offers a convenient way to track transactions. Record expected payment dates separately when preparing your forecast.
For additional financial-management guidance, visit the U.S. Small Business Administration’s business management resources. These resources explain bookkeeping, financial records, and other essential management practices.
Consider this hypothetical cash-flow example:
| Cash Movement | Amount |
|---|---|
| Available cash before Thanksgiving | $12,000 |
| Customer payments expected before holiday | +$4,000 |
| Payroll and related obligations | -$6,000 |
| Supplier invoices | -$3,500 |
| Rent and other scheduled payments | -$2,000 |
| Projected cash remaining | $4,500 |
Now suppose your business generates another $9,000 in weekend card sales. Those transactions may increase revenue without immediately increasing your available bank balance. Processing fees, refunds, and deposit timing can also affect the final amount received.
The example illustrates why a useful forecast includes dates rather than totals alone. A profitable weekend can still create a temporary cash shortage. Knowing when deposits should arrive helps you prepare for upcoming obligations.
Check Banking and Payroll Deadlines Early
Thanksgiving falls on Thursday, November 26, in 2026. The Federal Reserve observes the holiday, affecting normal banking and settlement operations. Review the Federal Reserve holiday schedule when planning business payments.
Effective Thanksgiving cash flow planning also requires checking payroll deadlines before the holiday. Ask your payroll provider when direct-deposit instructions must be submitted. Follow applicable payday requirements rather than assuming employees can simply be paid later.
Review supplier invoices and other payments scheduled for Thanksgiving week. Some businesses close for additional days or change their delivery schedules. Confirm deadlines early enough to make necessary adjustments.
Businesses handling cash deposits should also check their bank’s holiday arrangements. Branch closures do not necessarily eliminate every deposit option. Ask your financial institution when deposits will become available.
Understand When Card Sales Become Bank Deposits
A successful Black Friday or Small Business Saturday may produce impressive sales reports. However, those reports can include transactions that have not reached your account. That distinction becomes important when immediate expenses must be paid.
Review your payment processor’s settlement and payout schedule. Ask whether weekends, holidays, or account-specific restrictions affect deposit timing. Different providers may follow different procedures.
Remember that gross card sales are not identical to deposited funds. Processing fees, refunds, and adjustments can reduce the amount received. Use realistic net receipts when forecasting available cash.
If your business accepts several payment methods, review them separately. Card payments, ACH transfers, cash deposits, and instant-payment services can follow different schedules. Understanding those differences helps prevent avoidable surprises.
Avoid Tying Up Too Much Cash in Inventory
Holiday promotions can tempt business owners to purchase more inventory than necessary. Supplier discounts may appear attractive when sales expectations are high. However, excess merchandise can absorb cash needed for essential expenses.
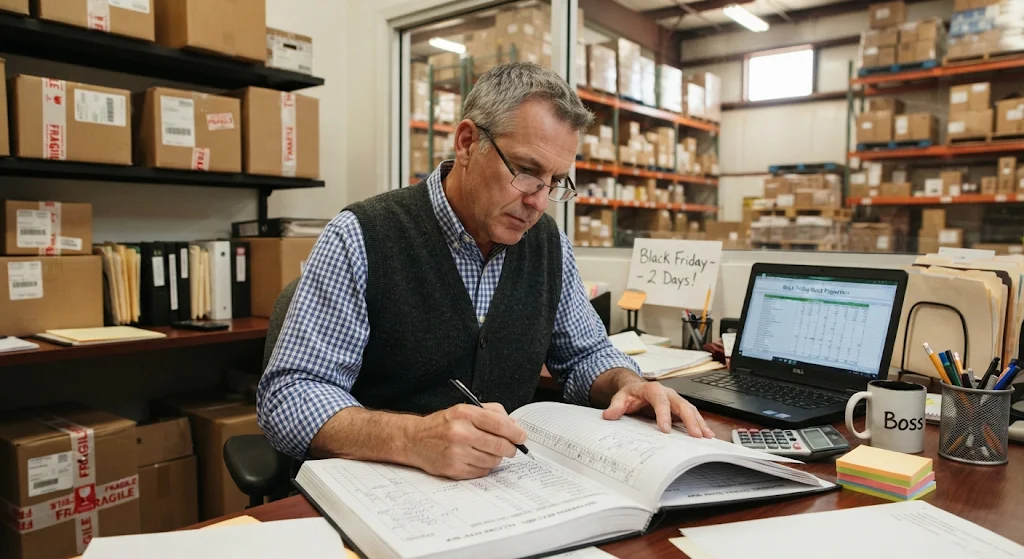
Review previous sales before ordering additional stock. Identify products with dependable demand and distinguish them from slower-moving merchandise. A smaller, carefully selected inventory may provide better financial flexibility.
Consider payment terms alongside purchase prices. An inexpensive order can still create difficulties when its invoice becomes due before the merchandise sells. Compare expected sales timing with your supplier’s deadline.
Businesses without retail inventory face similar choices. Restaurants may purchase extra ingredients, while service providers may increase supplies or staffing. Match those expenses to realistic demand rather than optimistic projections.
Prepare for Black Friday Through Cyber Monday
The Thanksgiving shopping period extends beyond one busy day. Black Friday, Small Business Saturday, and Cyber Monday can create different financial demands. Your plan should reflect the shopping patterns most relevant to your customers.
Estimate the costs associated with each promotion. Include advertising, staffing, packaging, shipping, and customer discounts. Strong revenue does not automatically produce strong profit margins.
Set spending limits before launching holiday promotions. If sales disappoint, those limits can reduce unnecessary financial strain. If demand exceeds expectations, reassess your plans using actual results.
Remember that holiday discounts are not appropriate for every business. Some owners may benefit more from maintaining normal prices and serving existing customers. Choose promotions that protect profitability rather than merely increasing sales volume.
Know When Short-Term Financing Makes Sense
A temporary cash shortage does not automatically mean your business needs another loan. First, determine whether the problem involves payment timing, weak profitability, or excessive expenses. Each situation calls for a different response.
If you anticipate a brief shortage, review existing reserves and available credit arrangements. Compare borrowing costs with the consequences of delaying nonessential purchases. Financing may help, but it should not be your automatic first choice.
If borrowing becomes necessary, examine interest, fees, repayment terms, and payment frequency. Fast financing can still carry substantial costs. Understand how repayment obligations will affect your December cash position.
Before applying, review what lenders look for in business bank statements. Understanding your financial records can help you prepare for lender questions. Accurate records also make it easier to identify weaknesses in cash management.
A dependable relationship with your lender can also be valuable. Our article about the benefits of a strong lender relationship explains why communication and preparation deserve attention.
Avoid borrowing based solely on hoped-for holiday sales. Use conservative estimates and consider what happens if revenue disappoints. Financing should address a manageable need rather than conceal a continuing financial problem.
Make a Plan for the First Week of December
The financial effects of Thanksgiving weekend do not end when promotions finish. Refunds, supplier invoices, payroll, and other obligations may arrive afterward. December can also introduce additional seasonal expenses.
Thanksgiving cash flow planning should continue into December as sales and payment information become clearer. Update your forecast using actual deposits and expenses. Investigate significant differences before committing to additional purchases.
Review which promotions produced worthwhile results. High sales may be less impressive after discounts, labor, advertising, and returns. Understanding the full cost helps you make better decisions next year.
Finally, consider how much cash your business should retain for unexpected expenses. Building reserves takes time, but modest progress improves flexibility. Regular cash reviews can reduce financial surprises throughout the year.
Your Thanksgiving Cash-Flow Checklist
Before the holiday arrives, give yourself time to review the essentials. The following checklist can help identify potential problems while there is still time to respond.
- Confirm available cash after outstanding payments.
- Forecast receipts and expenses through early December.
- Verify payroll submission deadlines and employee paydays.
- Check supplier deadlines and holiday delivery schedules.
- Review payment processor settlement and payout policies.
- Set realistic inventory and promotional spending limits.
- Maintain a reasonable cash cushion for unexpected costs.
- Reconcile holiday sales and deposits during the following week.
You do not need a perfect forecast to benefit from this exercise. You need a realistic picture of your obligations and available funds. That information allows you to make decisions before financial pressure limits your options.
A Stronger Holiday Begins With Preparation
Thanksgiving weekend can provide valuable opportunities for small businesses. It can also expose weaknesses in cash management that remain hidden during ordinary weeks. Preparing early gives you more choices when unexpected expenses arise.
Focus on available cash, realistic spending, and dependable payment dates. Those habits will continue serving your business long after the holiday season ends.
Photo Credit: All images © Sloan Digital Publishing and licensed stock sources. Used with permission.
Amazon Affiliate Disclosure: As an Amazon Associate, Business Loan Press may earn from qualifying purchases. This does not change the price you pay.