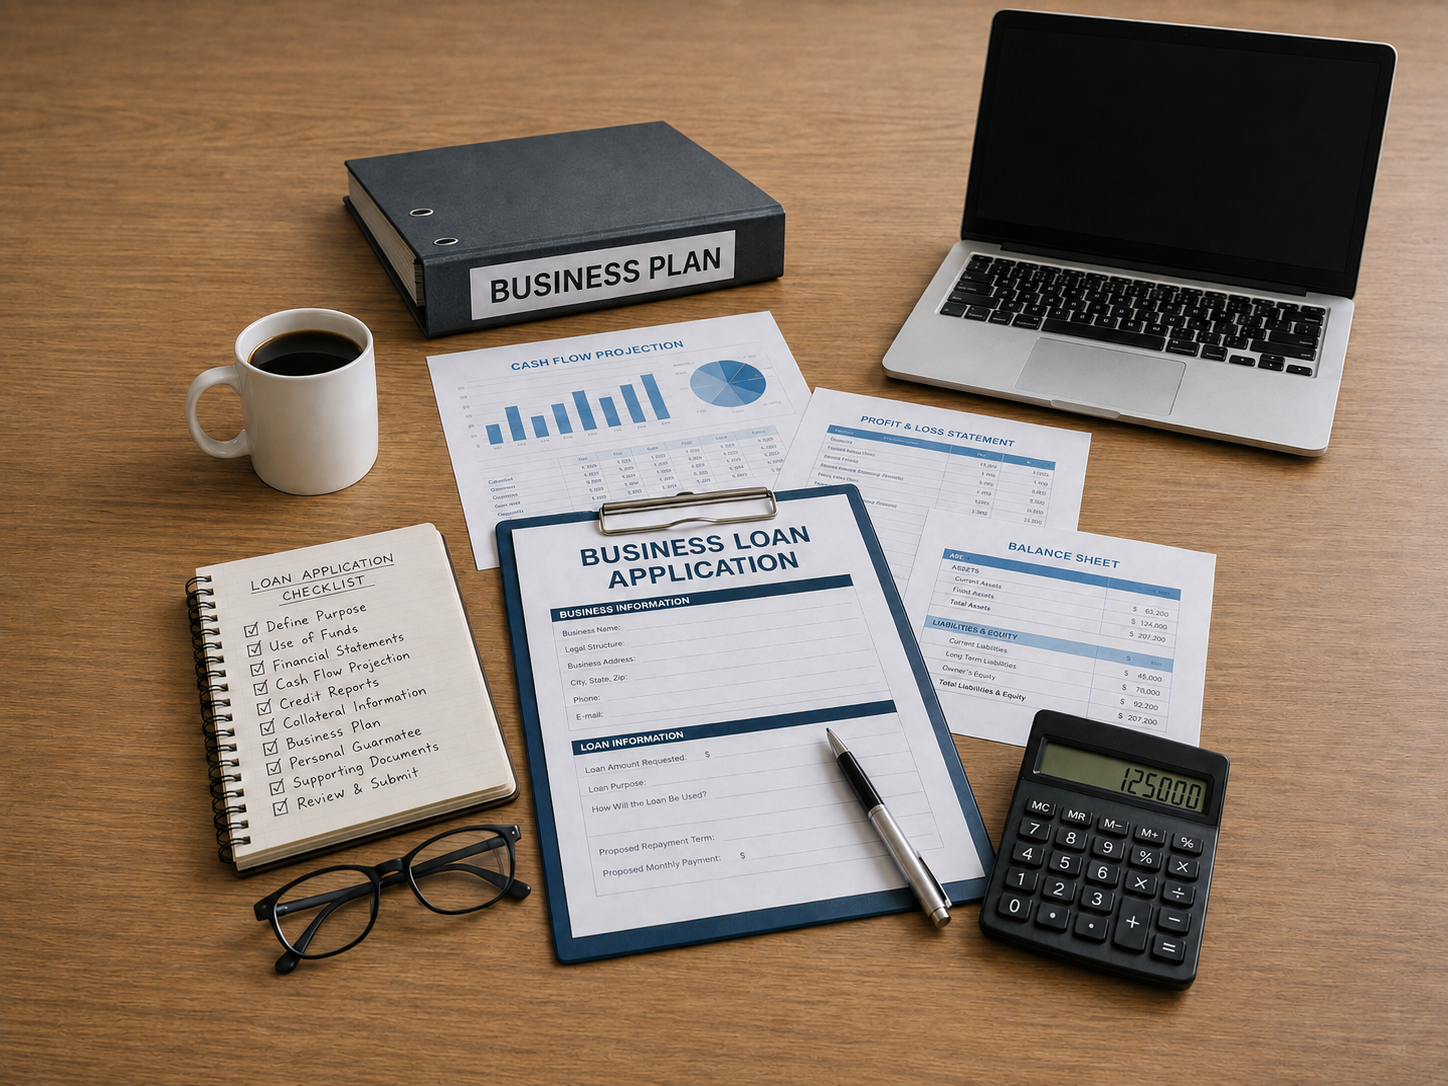
A strong business loan application gives a lender a clear and consistent picture of your company, its financing need, and its ability to repay the requested debt. Good credit can help, but it is only one part of the decision. Lenders may also examine cash flow, existing obligations, business records, management experience, collateral, and the intended use of the money.
Preparation cannot guarantee approval because lenders and financing programs use different underwriting standards. It can prevent avoidable problems such as requesting the wrong amount, submitting contradictory records, or approaching a lender whose products do not fit the business. Careful preparation can also help you recognize an offer that would place too much pressure on the company.
The goal is not merely to persuade someone to approve a loan. Your application should demonstrate that the request is well planned, the supporting information is dependable, and the proposed payment is manageable. The following guidance can help you prepare a credible application without presenting the business as stronger or safer than it really is.
Define the Exact Reason You Need Financing
Terms such as “working capital” and “business growth” describe broad purposes, but they do not explain what the loan will accomplish. Identify the specific expense, project, purchase, or temporary cash need the financing will address. The answer may involve equipment, inventory, real estate, renovations, debt refinancing, expansion, or the acquisition of another company.
The financing product should fit both the expense and the expected useful life of what the business is purchasing. A term loan may be appropriate for equipment that will serve the company for several years, while a line of credit may better fit recurring short-term needs. Using short-term financing for a long-lived asset can create unnecessarily high payments and strain cash flow.
Before approaching a lender, write one clear sentence explaining what the business will do with the money. Then explain how the expenditure is expected to increase revenue, lower costs, improve operations, or solve a temporary timing problem. When that explanation remains vague, the financing request usually needs more development.
Request an Amount Supported by Real Costs
A strong business loan application should explain how the requested amount was calculated. Choosing a convenient round number without supporting evidence can make the request appear poorly planned. Build the total from vendor estimates, equipment quotes, construction bids, inventory costs, closing expenses, deposits, professional fees, or other documented needs.
Create a use-of-funds schedule that lists each anticipated expense and any contribution the owners will make. Include related costs that are easy to overlook, such as delivery, installation, permits, software, training, insurance adjustments, or a reasonable working-capital reserve. The lender should be able to see where the money will go and why each expense is necessary.
Borrowing too little can leave the company making payments before the project is complete. Borrowing substantially more than necessary can increase interest expense and weaken repayment capacity. The most defensible request is one tied to realistic costs and a clear plan for every portion of the funds.
Demonstrate Realistic Repayment Capacity
Revenue and profit do not automatically prove that a business can make a new loan payment. A profitable company can still experience cash shortages when customers pay slowly, inventory must be purchased early, or seasonal expenses arrive before related income. Lenders therefore pay close attention to the cash available after payroll, rent, taxes, existing debts, and other operating expenses are paid.
Prepare a realistic cash-flow projection that includes the proposed payment. Base the forecast on supportable assumptions rather than the strongest result the company could possibly achieve. When sales or expenses fluctuate during the year, the projection should reflect both the stronger and weaker months.
Test the payment under less favorable conditions before applying. Consider whether the business could continue paying if revenue declined temporarily, a major customer paid late, or an important expense increased. A reasonable financial cushion is more reassuring than a forecast showing that every available dollar must be used to keep the loan current.
Strengthen Your Business Loan Application With Consistent Records
A lender may request tax returns, bank statements, profit-and-loss statements, balance sheets, debt schedules, and accounts receivable or payable reports. These documents do not have to contain identical figures because they serve different accounting purposes. Significant differences should nevertheless be understandable and supported by an explanation.
Review the entire application package before submitting it. Revenue shown on the financial statements should make sense when compared with tax returns and deposits, while debt balances should agree with the company’s debt schedule. Ownership percentages, legal names, addresses, and identifying details should also remain consistent throughout the application.
Legitimate differences may result from accounting methods, timing, transfers, owner contributions, or one-time transactions. Prepare a concise explanation instead of assuming the lender will recognize the cause. For a broader document list, review the items banks may request before approving a business loan.
Some very small businesses still maintain part or all of their records manually. A structured monthly bookkeeping record can help an owner track income, expenses, payroll, and year-end totals in one place. It does not replace professional accounting advice or the financial statements a lender may require, but it can make routine recordkeeping more consistent.
Review Personal and Business Credit Before Applying
A lender may review the company’s credit history, the owners’ personal credit, or both. Personal credit often has greater importance when a business is new or has not established a substantial credit file. Obtain the appropriate reports early enough to examine them carefully before submitting an application.
Look for incorrect balances, duplicate collections, accounts that do not belong to you, and payments inaccurately reported as late. Use the reporting agency’s established dispute process to challenge legitimate errors and retain documentation of the correction. Avoid paying anyone who promises to remove accurate negative information or create a new credit identity.
Accurate problems may still require an explanation. High balances, missed payments, collections, tax problems, or recent delinquencies can raise concerns about repayment, but a factual account may provide useful context. Explain what happened, how the problem was resolved, and what has changed to reduce the chance of recurrence.
Support Financial Projections With Evidence
Financial projections are especially important for startups, acquisitions, expansions, new locations, and equipment purchases expected to change future performance. A spreadsheet showing steadily increasing sales is not persuasive by itself. A strong business loan application connects projected results to evidence the lender can examine.
Supporting evidence may include signed contracts, purchase orders, customer history, pricing information, documented demand, current production limits, or the expected output of new equipment. Explain when the project is likely to begin producing income or reducing expenses. Include the period when the business may be paying for construction, installation, training, or marketing before receiving the full benefit.
Expense projections deserve as much attention as projected revenue. Include payroll, maintenance, supplies, utilities, insurance, taxes, professional services, and other costs associated with growth. SCORE also offers financial-projection and business-planning resources that can help owners test assumptions before presenting them to a lender.
Show That Management Can Carry Out the Plan
Lenders finance businesses, but people remain responsible for carrying out the plan and managing the repayment obligation. Describe the experience that is directly relevant to the company, industry, and proposed project. A clear explanation of practical qualifications is more useful than a long résumé containing unrelated accomplishments.
When the management team lacks an important skill, explain how the gap will be addressed. The business may rely on an accountant, attorney, experienced manager, contractor, consultant, or other qualified professional. Recognizing the need for outside expertise can demonstrate sound judgment rather than weakness.
A formal business plan may be particularly useful for a startup, acquisition, substantial expansion, or new line of business. An established company seeking a straightforward equipment purchase may not need the same level of detail, but management should still be able to explain the market, operations, use of funds, risks, and repayment strategy. Free planning assistance may be available through SCORE and other SBA resource partners.
Understand Collateral and Personal Guarantees
Collateral gives a lender a possible secondary source of recovery if the loan is not repaid. It does not replace the need for sufficient cash flow and a reasonable ability to make scheduled payments. The business should expect normal operations, rather than the sale of pledged assets, to provide the primary source of repayment.
Prepare information about equipment, vehicles, inventory, accounts receivable, real estate, and other assets the lender may consider. Include current ownership, estimated value, and any existing liens. Remember that the value assigned by a lender may be lower than the purchase price or the amount shown on the company’s balance sheet.
A loan described as unsecured may not require one specific asset to be pledged, but the agreement could still contain a personal guarantee or a broad lien against business property. Ask what assets and personal obligations would be exposed if the company defaults. Do not offer collateral or sign a guarantee until you understand the potential consequences.
Compare Lenders and the Complete Cost of Each Offer
Different lenders may reach different conclusions about the same business. Banks, credit unions, SBA-participating lenders, nonprofit lenders, equipment finance companies, and online lenders may serve different borrowers. Begin by determining whether the lender regularly finances your type of company, loan purpose, requested amount, and stage of development.
Compare more than the advertised interest rate. Review the annual percentage rate when available, origination fees, closing costs, payment amount, payment frequency, total repayment, collateral requirements, guarantees, prepayment provisions, and default terms. Daily or weekly withdrawals may create substantially more pressure than monthly payments when business revenue arrives irregularly.
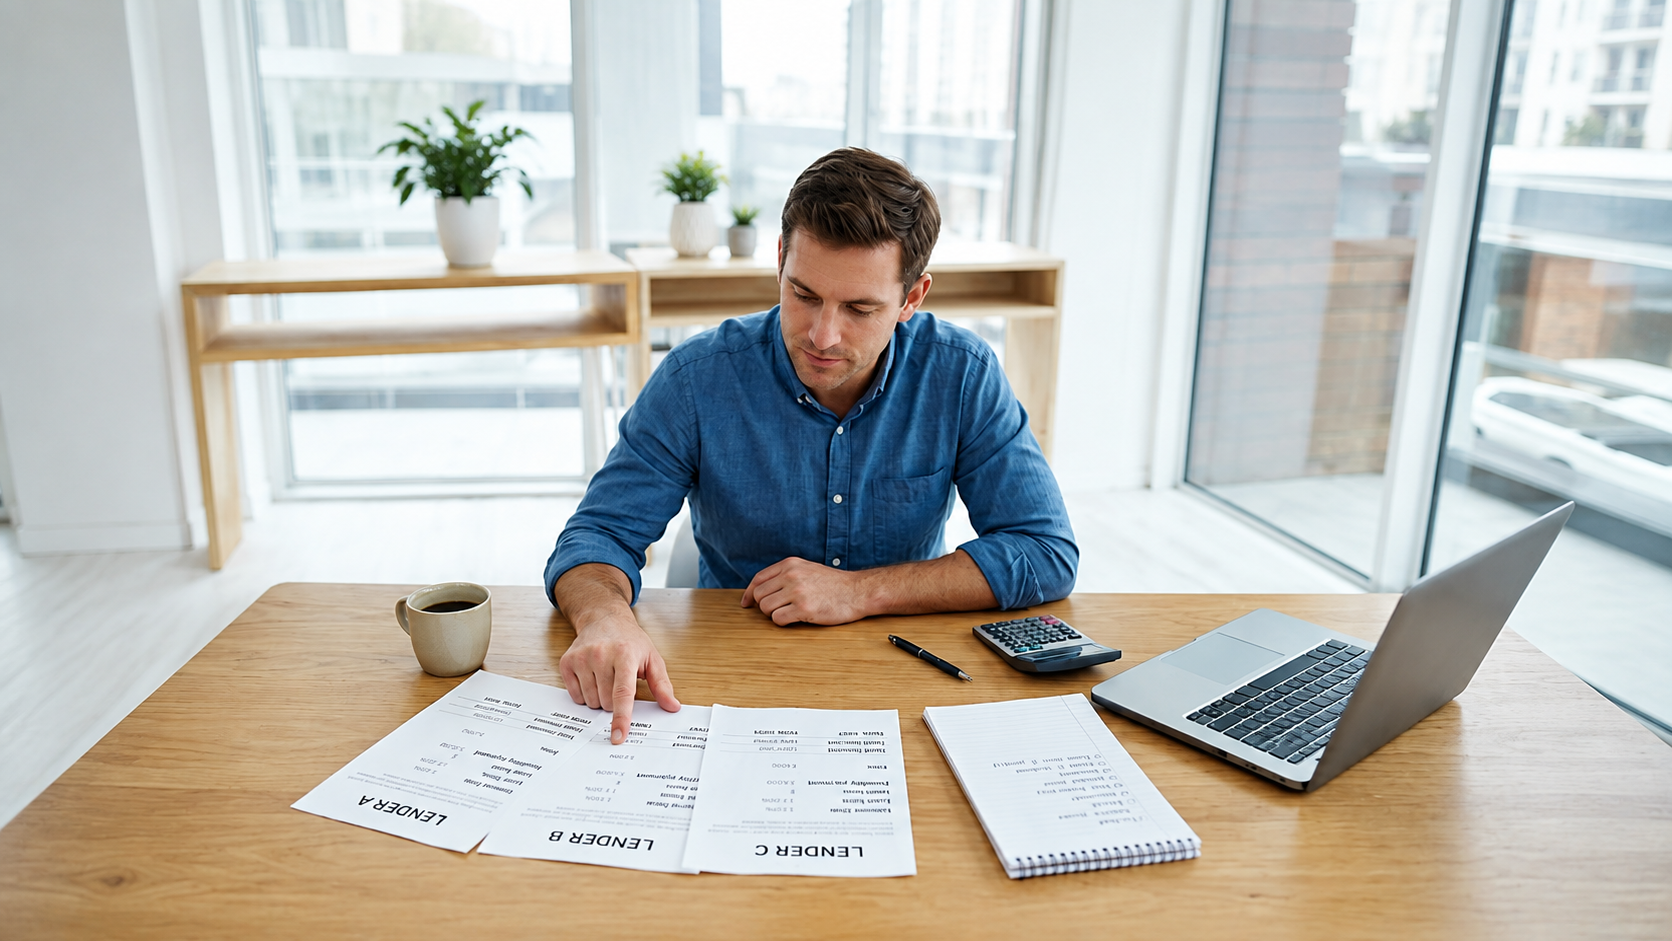
Read every agreement and compare written terms with what the salesperson or lender representative told you. Do not sign incomplete documents, leave blank spaces for someone else to fill in, or accept pressure to decide immediately. Our guide to applying safely for a small business loan explains additional warning signs to consider.
Know When the Business Should Delay Applying
Applying immediately is not always the best choice. Consider waiting when financial records are incomplete, tax filings remain unresolved, recent banking activity cannot be explained, or the company cannot demonstrate how it will make the proposed payment. A vague funding purpose or unsupported loan amount is another sign that the application needs more preparation.
Repayment should not depend entirely on aggressive growth, one unconfirmed customer, or the immediate success of an untested product. New debt should support a credible plan rather than substitute for one. Delaying may provide time to improve credit, reduce existing obligations, strengthen cash reserves, or gather better documentation.
When a previous application has been declined, ask for the principal reasons behind the decision when that information is available. Correcting the underlying weakness is generally more useful than presenting the same application to several additional lenders. Owners who are concerned about unequal access to credit may also find our discussion of women and business-loan approval helpful.
Strong Business Loan Application Checklist
Use this checklist before sending documents to a lender. Each answer should be specific enough that someone unfamiliar with the company can understand it. Any item that remains vague, unsupported, or inconsistent should be corrected before the application is submitted.
- State the exact purpose of the financing.
- Explain how the requested amount was calculated.
- Provide a detailed use-of-funds schedule.
- Identify any owner contribution.
- Show the expected source of repayment.
- Include the proposed payment in the cash-flow forecast.
- List existing debts, liens, and monthly obligations.
- Review personal and business credit reports.
- Explain significant credit problems or unusual transactions.
- Reconcile tax returns, bank statements, and financial reports.
- Support projected revenue and expenses with reasonable assumptions.
- Describe management’s relevant experience and responsibilities.
- Understand all collateral and personal-guarantee requirements.
- Compare the complete cost and terms of suitable offers.
- Read every financing document before signing it.
Build a Strong Business Loan Application That Supports a Sound Decision
A strong business loan application does not portray the company as flawless. It presents an accurate, organized, and supportable explanation of the business, the financing need, the risks involved, and the plan for repayment. A strong business loan application helps the lender evaluate the request while also helping the owner decide whether the debt is genuinely affordable.
Approval should not be pursued at any cost. The better outcome is financing that addresses a legitimate need, carries understandable terms, and leaves the company enough flexibility to operate when conditions are less favorable than expected. A careful application process can therefore protect the business even when the final answer is not the one the owner originally hoped to receive.
Sources
- U.S. Small Business Administration: Loans
- U.S. Small Business Administration: 7(a) Loans
- U.S. Small Business Administration: Lender Match
- SCORE: Financial Projections Template
- SCORE: Business Planning Resources
Editor’s Note: This article was updated and substantially expanded in August 2026 to provide current guidance on building a complete, consistent, and supportable business loan application.
Financial Information Disclaimer: This article provides general educational information and is not financial, legal, accounting, tax, or lending advice. Loan requirements, underwriting standards, costs, and approval decisions vary by lender and financing program. Review all financing documents carefully and consult qualified professionals regarding your individual business circumstances.
Amazon Affiliate Disclosure: As an Amazon Associate, Business Loan Press may earn from qualifying purchases. This does not change the price you pay.
Photo Credit: All images © Sloan Digital Publishing and licensed stock sources. Used with permission.



celebrities
Howdy! I just wish to give you a big thumbs up for the excellent info you have here on this post. I am returning to your web site for more soon. Casey Benjie Mason